
Introduction: The Sixteen-Cent Clue
Buried inside the more than 260 pages of Anthropic’s confidential initial-public-offering prospectus, roughly eighty of which are devoted to risk factors, is a number that may eventually matter more to the economics of artificial intelligence than any benchmark score, parameter count or model launch announced in the same year.[2] It is not the company’s targeted valuation of approximately $2 trillion, nor its twelvefold revenue growth to nearly $4.6 billion in 2025, nor even the $518 billion of cloud, compute and infrastructure obligations that the company expects to assume over the coming decade.[3] It is a far smaller and far more revealing figure.
It is sixteen cents.
On September 29 and 30, 2026, Reuters reported, on the basis of a copy of the confidential filing it had reviewed, that Anthropic pays roughly sixteen cents to major technology platforms for every dollar of revenue it generates through certain cloud marketplace channels.[1] The precise distinction matters enormously and will matter throughout this paper. Reuters did not report that sixteen percent of all Anthropic revenue goes to its cloud partners. Rather, according to the filing, approximately $2.16 billion, or 47 percent of Anthropic’s 2025 revenue, was generated through the Amazon and Google cloud marketplaces, and Anthropic paid approximately $351 million in distribution fees associated with those sales, which works out to roughly sixteen cents for every marketplace dollar.[1] Anthropic records the full value of the customer contract as revenue, on the grounds that it sets the price and delivers the service, and it then records the platform’s share within its “sales, marketing, and partnerships” operating expense line.[4]
At first glance, this might appear to be an accounting footnote of the kind that interests only revenue-recognition specialists and the analysts who must reconcile competing presentations between rival laboratories. It is nothing of the sort. The disclosure exposes something fundamental about the emerging industrial structure of artificial intelligence, and it does so with an empirical precision that was previously unavailable to anyone outside the companies themselves. Anthropic develops Claude. Anthropic employs the researchers. Anthropic trains the models. Anthropic controls the model architecture, the safety systems, the application programming interfaces, the product strategy and the intellectual property. Yet when Claude reaches many of its enterprise customers, a measurable part of the economic value created by that intelligence passes through companies that sit elsewhere in the stack, and those companies retain a share of it as a matter of contractual course.
Amazon and Google are not ordinary resellers in the sense that a software distributor of the 1990s was a reseller. They provide computing capacity. They operate datacenters. They design or commission the specialized accelerators on which frontier models are trained and served. They maintain global cloud networks. They control established enterprise marketplaces with billing, identity, procurement and compliance machinery already in place. They already hold contractual relationships with many of the corporations that Anthropic wishes to acquire as customers. They invest capital in Anthropic, and at the same time they develop competing artificial-intelligence products of their own. Reuters summarized the unusual geometry of the arrangement clearly when it observed that the same two companies that supercharge Anthropic’s distribution and collect customer bills on its behalf are also large investors, critical suppliers of computing power and direct rivals in artificial intelligence.[1]
This is precisely the point at which the economics of frontier artificial intelligence begin to depart from the conventional software story that investors have been trained for three decades to apply. The great software companies of the previous generation benefited from an extraordinarily attractive economic assumption: once the software had been written, producing another copy cost almost nothing. A software-as-a-service company could add another customer without constructing a power plant, buying thousands of accelerators, securing additional high-bandwidth memory, expanding a datacenter or reserving gigawatts of electricity. Frontier intelligence is different in kind rather than merely in degree, because every additional unit of useful artificial intelligence has a physical ancestry. Behind an answer generated by Claude, by ChatGPT, by Gemini or by any other frontier system lies a chain extending backward through inference servers, accelerators, networking equipment, memory, cooling infrastructure, datacenters, substations, transmission systems and power generation. Training pushes that requirement further still, because increasingly capable models require not merely software engineers but enormous commitments to physical capacity that must be financed, built, powered and depreciated.
Anthropic itself illustrates the transformation with unusual clarity. According to the prospectus as reported, the company spent approximately $7.33 billion on compute and infrastructure in 2025, roughly three times the prior year’s figure and more than half of its $12.65 billion in total operating expenses, while its operating loss widened to $8.06 billion from $2.98 billion.[5] At the end of 2025 it carried $54.6 billion of non-cancellable hosting and computing commitments, and by early 2026 its total long-term commitments exceeded $417 billion, covering roughly 3.5 gigawatts of dedicated computing capacity.[1] And Anthropic is expanding rather than escaping those relationships. In April 2026 it announced an agreement with Amazon under which it will commit more than $100 billion over ten years to Amazon Web Services technologies in exchange for up to five gigawatts of Trainium capacity, with Amazon investing a further $5 billion immediately and up to $20 billion more tied to commercial milestones.[6] Two weeks earlier it had signed an agreement with Google and Broadcom for approximately 3.5 gigawatts of next-generation Tensor Processing Unit capacity expected to come online starting in 2027.[7] The company simultaneously maintains a diversified hardware strategy incorporating Amazon Trainium, Google TPUs and Nvidia GPUs, and it distributes Claude through AWS Bedrock, Google Cloud Vertex AI and Microsoft Azure Foundry, explicitly arguing in its prospectus that these platforms give it access to enterprise distribution at a scale that would be, in the filing’s own words, “difficult for any single organization to directly replicate.”[1]
All of this creates a remarkable economic loop, and the loop is the central subject of this paper. The cloud company invests money into the model laboratory. The laboratory spends enormous sums purchasing computing capacity from the cloud company. The cloud company distributes the laboratory’s model through its marketplace. Enterprise customers pay the cloud company. The cloud company retains a portion of the transaction and remits the remainder to the laboratory. The same cloud company may simultaneously train its own competing models, build its own accelerators and use information drawn from its enormous enterprise ecosystem to decide where future infrastructure investment should go. Capital moves downward into infrastructure. Compute moves upward toward models. Models move upward toward applications. And revenue moves downward again, retracing the path along which the intelligence was created.
Capital ↓ Infrastructure
Compute ↑ Models
Models ↑ Applications
Revenue ↓ Infrastructure
Within the Five-Layer AI Economy, a framework developed across my earlier papers and extended here, we can describe the industrial system in which this loop operates as a stack of five interdependent layers, each of which possesses its own scarcity, its own capital intensity and its own claim on the value generated above it.
| Layer | Name | What It Contains |
| Layer 1 | Energy | Electricity generation, grids, substations, transmission and increasingly dedicated and behind-the-meter power systems |
| Layer 2 | Chips | GPUs, TPUs, Trainium, custom accelerators, high-bandwidth memory, networking silicon and advanced packaging |
| Layer 3 | Datacenters and Cloud Infrastructure | Hyperscale campuses, computing clusters, cloud platforms, networks, storage, billing systems and enterprise marketplaces |
| Layer 4 | Models | Claude, GPT, Gemini and other foundation and frontier models |
| Layer 5 | Applications and Agentic Systems | Enterprise applications, consumer products, autonomous agents and workflows that convert intelligence into economic activity |
Much of the public discussion of AI economics assumes, often without stating the assumption, that extraordinary value creation at Layers 4 and 5 will naturally result in extraordinary margin capture by the companies operating there. Cloud Tithe challenges that assumption directly. The central thesis of this paper is that frontier-model economics contain a structurally persistent infrastructure toll, and that model laboratories cannot necessarily capture all of the economic value generated by their intelligence because reaching customers at enormous scale requires infrastructure, distribution, billing systems, accelerators, datacenters and enterprise channels that are owned by companies below them in the Five-Layer AI Economy. This does not mean that cloud providers automatically dominate model companies, nor that current fee structures will remain unchanged. Model laboratories are already attempting to create bargaining power through multicloud strategies, custom hardware relationships, direct enterprise sales, enormous dedicated computing projects and increasingly diversified infrastructure arrangements. The economically important question is therefore not whether the tithe exists, because the prospectus has now established that it does. The question is how large the tithe will become, who will collect it, what services will justify it, and when frontier laboratories will become powerful enough to renegotiate it or to integrate vertically around it. That question takes us beyond the familiar debate about which model is smartest and toward something more fundamental about the industrial organization of the coming decade: who gets paid every time intelligence is consumed?
Why I Chose the Title “Cloud Tithe”
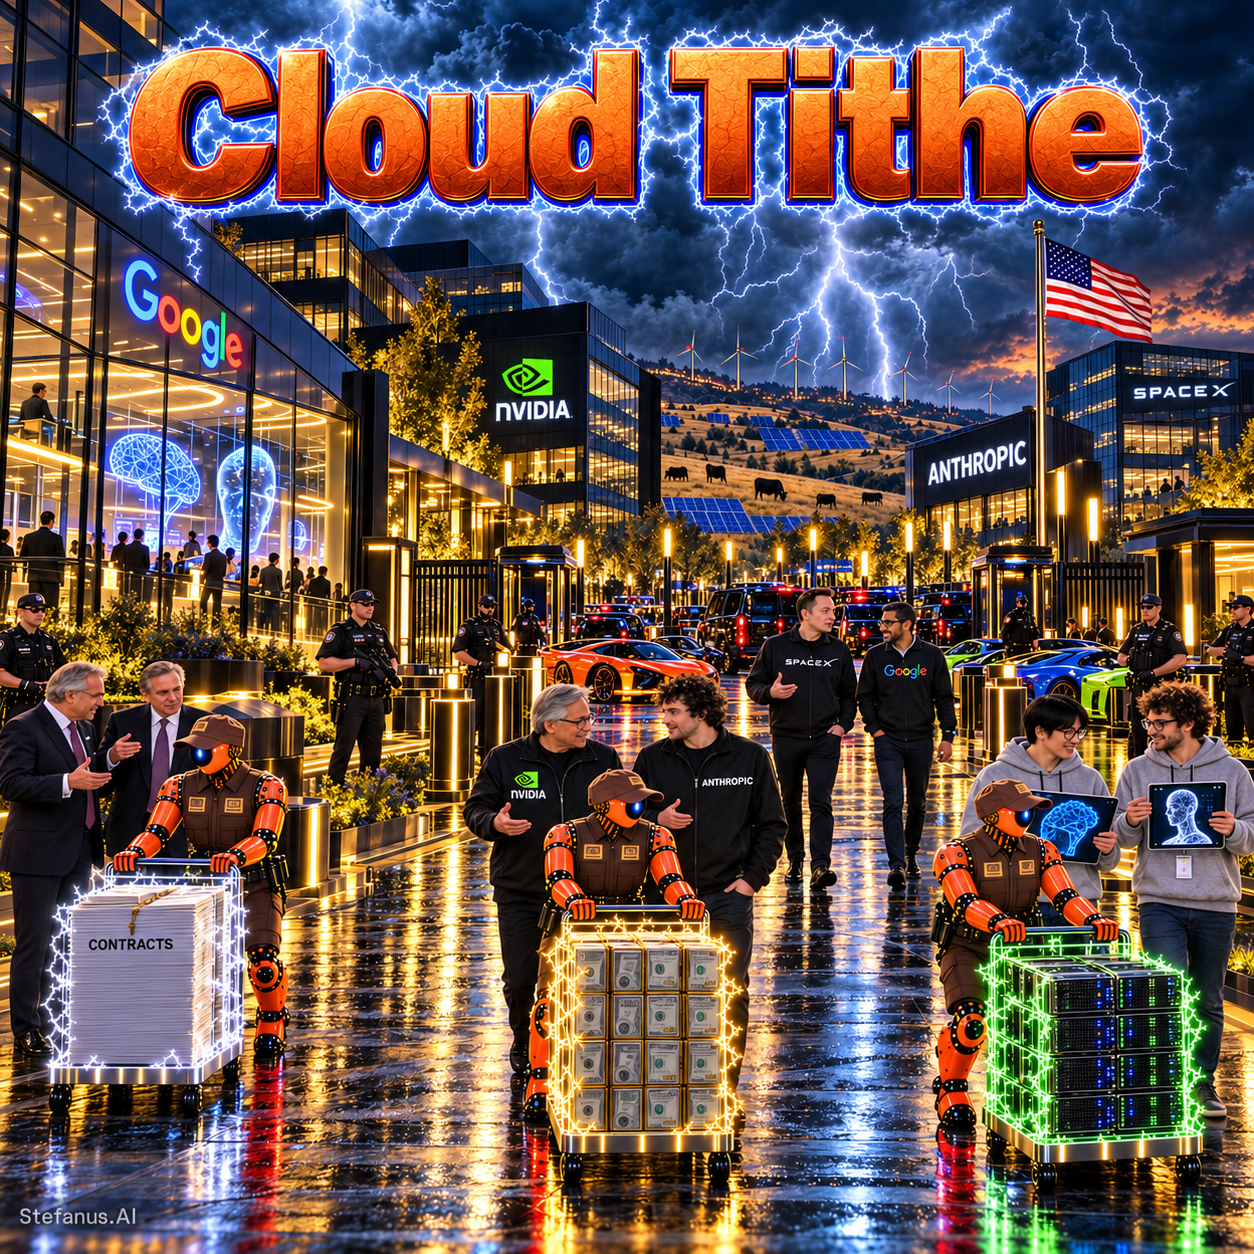
I chose the title Cloud Tithe because the word tithe captures, better than any alternative I considered, the recurring and proportional nature of the economic relationship that the Anthropic prospectus has made visible. Historically, a tithe described a share of economic production that was transferred, regularly and as a matter of institutional obligation rather than individual negotiation, from the producer to another institution that stood above or beside the producer in the social order. I use the term metaphorically and with some care. The cloud tithe is not a government tax, and the term does not imply that cloud providers receive money without providing value. Amazon Web Services, Google Cloud, Microsoft Azure and the other infrastructure providers supply scarce compute, global distribution, security, billing relationships, enterprise procurement channels and increasingly the specialized silicon on which frontier models operate. But when a measurable portion of every qualifying artificial-intelligence transaction repeatedly flows toward that infrastructure layer, the relationship begins to resemble a continuing claim on the economic production of intelligence rather than an ordinary one-time technology purchase, and it is that continuing and proportional quality that distinguishes a tithe from a capital expenditure.
The title also fits the Five-Layer AI Economy because it describes the direction of value redistribution. Intelligence may be invented in Layer 4 and monetized through Layer 5, yet part of its revenue can move downward toward Layer 3 cloud infrastructure, Layer 2 accelerators and ultimately Layer 1 electricity. Cloud Tithe therefore turns the conventional AI value-chain question upside down. Instead of asking only which company creates the best model, the paper asks which companies can establish recurring claims on the revenues generated by those models. That is why Cloud Tithe is the natural counterpart to my earlier Central Bank of AI thesis. One examines who supplies the scarce compute liquidity required by the AI economy; the other examines who keeps collecting economic value after that liquidity has been transformed into intelligence and sold. The first is a question about the supply of a scarce input. The second is a question about the distribution of the output. Together they describe a system in which the same handful of institutions sit at both ends of the pipe.

Section 1: When Software Economics Meets the Physical Cost of Intelligence
Before the paper can examine the particular contractual geometry of Anthropic’s relationships with Amazon and Google, it must first establish why that geometry is economically significant at all, and that requires an understanding of the assumptions investors inherited from the software era and of the specific ways in which frontier intelligence violates them. This section therefore begins with the gross-margin inheritance of the software industry, proceeds through the proposition that intelligence carries a variable cost, distinguishes the economics of training from the economics of inference, introduces the marketplace fee as a second and separate layer of infrastructure claim, examines the accounting controversy that the fee has already generated, and closes with the margin cascade that will serve as the paper’s recurring visual framework.
1.1 The Gross-Margin Inheritance from the Software Era
Investors apply software economics to AI companies instinctively, and the instinct is understandable, because the historical record of the software industry is one of the most remarkable in the history of capitalism. Traditional software benefited from negligible reproduction costs. Development might be expensive, sometimes extraordinarily so, but distributing one additional copy of an application required little incremental physical investment, and the result was an industry in which gross margins of seventy, eighty or even ninety percent became not merely achievable but expected. The entire discipline of software valuation, from the rule of forty to the net-revenue-retention metrics beloved of venture investors, was built upon the assumption that the marginal cost of serving the next customer approaches zero and that the economic problem is therefore one of customer acquisition rather than of production.
Frontier AI changes that assumption because utilization itself consumes scarce computing resources, and it is important to distinguish carefully among several activities that are too often collapsed under a single heading. Software replication, in which a compiled artifact is copied to a new machine, remains nearly free. Software-as-a-service hosting, in which a vendor operates the application on shared infrastructure, carries a modest but real cost that successful companies learned to amortize across millions of users. Model training, in which enormous clusters of accelerators are run for weeks or months to produce a new set of weights, carries a cost measured in hundreds of millions or billions of dollars per generation. Model inference, in which a trained model is run to answer a query, carries a cost per token that is small but strictly positive and that scales with usage. Reasoning-intensive inference, in which a model generates long internal chains of thought before answering, multiplies that cost by a factor that can reach into the dozens. Multimodal generation, particularly of video, multiplies it again. And agentic workloads, in which a single user request triggers hundreds or thousands of internal model calls, tool invocations and computational operations, represent the frontier of infrastructure intensity. As AI systems perform longer reasoning chains, generate richer media, operate autonomous agents and maintain persistent memory across sessions, the incremental cost of serving intelligence remains economically material even as the cost of any single unit of intelligence falls.
1.2 Intelligence Has a Variable Cost
One of the central propositions of this paper can be stated in a single sentence that I will return to repeatedly: software can be copied, but intelligence must be computed. Every incremental AI workload consumes some combination of accelerator time, high-bandwidth memory capacity, networking bandwidth, storage, cooling and electricity, and those inputs are not free, are not infinitely available and are not owned, in most cases, by the laboratory that created the model. That single fact converts infrastructure from a background information-technology expense, of the kind that software companies disclosed in a footnote about hosting costs, into a direct and dominant component of the AI product’s cost of goods sold. The economics of Layer 4 therefore cannot be analyzed independently from Layers 1 through 3, any more than the economics of an airline can be analyzed independently from the price of jet fuel.
This proposition is sometimes challenged on the grounds that inference costs are collapsing, and the evidence for that collapse is real and striking. Stanford University’s Institute for Human-Centered Artificial Intelligence reported in its 2025 AI Index that the cost of querying a model performing at the level of GPT-3.5 on the MMLU benchmark fell from $20 per million tokens in November 2022 to $0.07 per million tokens by October 2024, a reduction of more than 280-fold in approximately eighteen months, and that depending on the task, inference prices have fallen anywhere from nine to nine hundred times per year.[8][9] At the hardware level, the Index estimated that costs have declined by roughly thirty percent annually while energy efficiency has improved by roughly forty percent per year.[8] These are extraordinary numbers, and any honest analysis of the Cloud Tithe must take them seriously. But the collapse in the cost of a fixed level of capability does not imply a collapse in the total infrastructure bill, because the frontier of demanded capability moves faster than the cost curve, and because falling unit costs induce vastly greater consumption, a dynamic that economists since William Stanley Jevons have recognized in coal, in computing and now in tokens. Anthropic’s compute and infrastructure expense tripled in 2025 even as per-token prices fell, and the company’s annualized revenue run rate rose from roughly $9 billion at the end of 2025 to $65 billion by the end of July 2026, a sevenfold increase in seven months that could not have occurred without a proportionate expansion in the physical capacity required to serve it.[10] Stanford’s Erik Brynjolfsson captured the behavioral side of this dynamic when he observed, in a July 2026 conversation about the AI productivity curve, that only months earlier enterprises had been consuming tokens without much regard for their price.
Just a few months ago, people were “tokenmaxing” without worrying about token cost.
— Erik Brynjolfsson, Stanford Digital Economy Lab [11]
The lesson is that cheap intelligence is not the same as cheap infrastructure. The former describes the price of a unit; the latter describes the size of the aggregate claim, and it is the aggregate claim, not the unit price, that determines how much of a laboratory’s revenue must flow downward to the layers beneath it.
1.3 Training Costs and Inference Costs Are Economically Different
It is essential to separate the enormous periodic expense of creating new frontier models from the recurring expense of serving them, because the two behave differently in a laboratory’s financial statements and because they create different kinds of dependence on the infrastructure layer. Training resembles a massive research and production investment, lumpy in timing, concentrated in a small number of very large clusters, and justified by the expectation that the resulting model will generate revenue over a product lifetime that is currently measured in months rather than years. Inference behaves more like a variable manufacturing cost, continuous in timing, distributed across many regions and many hardware platforms, and scaling more or less linearly with the number of tokens customers consume. A laboratory that owned its training infrastructure but rented its inference infrastructure would face one kind of exposure to the cloud; a laboratory that rented both would face another; and a laboratory that, like Anthropic, has committed to specific accelerator architectures across both activities faces a third, in which the portability of its workloads becomes a strategic variable.
Agentic AI complicates the distinction further, because one user request may now create hundreds or thousands of internal model calls, tool calls and computational operations, so that the boundary between a single inference and a sustained computational session dissolves. Nvidia’s founder and chief executive Jensen Huang described the resulting shift in his company’s February 2026 results, when he observed that computing demand was growing exponentially because the agentic inflection point had arrived, and by August 2026 he had reduced the proposition to its starkest form.
Now, compute is revenue.
— Jensen Huang, Founder and CEO, Nvidia [12]
The statement is revealing precisely because of who made it. For a chip vendor, compute is revenue in the most literal sense. For a model laboratory, compute is cost of goods sold, and the next generation of AI may therefore increase customer value while simultaneously increasing infrastructure intensity, so that revenue and infrastructure claims grow together rather than diverging in the manner that software investors have come to expect.
1.4 The Marketplace Fee Adds Another Layer
Compute expense, however large, is not the entire Cloud Tithe, and the single most important analytical contribution of the Anthropic disclosure is that it separates two claims that are often confused. A frontier laboratory can pay once for the infrastructure required to produce intelligence and then pay again for access to the enterprise distribution channels through which that intelligence is sold. The Reuters reporting on Anthropic makes this visible with unusual precision. Approximately $2.16 billion of Anthropic’s 2025 sales flowed through the Amazon and Google cloud marketplaces, and roughly $351 million then flowed back to those platforms as distribution fees, recorded not in cost of revenue but within sales, marketing and partnership expense.[1] That $351 million is entirely distinct from the $7.33 billion of compute and infrastructure expense recorded elsewhere in the income statement. The important analytical distinction can therefore be stated as an inequality that the rest of this paper will treat as foundational:
Compute Cost ≠ Distribution Cost
A laboratory can face several overlapping infrastructure claims on the same unit of intelligence. It pays the cloud provider for the accelerator hours that generate the response. It pays the same or a different cloud provider a percentage of the contract value for the privilege of reaching the customer through a marketplace that the customer already trusts. It may pay a third claim in the form of revenue sharing embedded in a strategic partnership, as OpenAI does with Microsoft. And it bears, indirectly, the cost of the memory, the packaging, the networking and the electricity that the cloud provider must itself procure. The sixteen-cent figure captures only the second of these claims, which is why it should be read as a lower bound on the total tithe rather than as an estimate of it.
1.5 Gross Revenue, Net Revenue and the Optics of AI Scale
The marketplace fee has already generated an accounting controversy that illustrates how little settled vocabulary exists for frontier-model economics. Anthropic recognizes the gross value of certain marketplace contracts as revenue and records the cloud marketplace portion separately as an operating expense, on the stated grounds that it is the principal in the transaction because it sets prices and delivers the service.[1] Reuters reported in June 2026 that OpenAI had told investors and employees that this approach inflates Anthropic’s reported revenue by billions of dollars, and that OpenAI itself uses a different presentation for comparable arrangements, recognizing only what it retains after the cloud partner’s portion.[1] Anthropic responded that it follows established accounting practices. Both positions can be defensible under the relevant standards, because principal-versus-agent determinations turn on facts about control and pricing authority that outsiders cannot verify, and neither presentation by itself answers the economic question that investors actually care about, which is how much of each customer dollar the laboratory ultimately keeps.
The practical consequence, as the financial-education publisher Finimize observed in its coverage of the filing, is that many IPO investors will likely “re-net” Anthropic’s marketplace sales in order to compare it with other laboratories on a like-for-like basis.[13] For investors who wish to do that re-netting systematically, the more useful metrics may eventually include a hierarchy of revenue and margin concepts that distinguish each layer of infrastructure claim from the next.
| Metric | Definition | What It Reveals |
| Direct Revenue | Revenue generated through the laboratory’s own sales channel and billing relationship | The portion of the business that carries no marketplace claim |
| Marketplace Revenue | Revenue distributed through external cloud platforms that collect the customer’s payment | Exposure to channel fees, channel concentration and collection risk |
| Infrastructure-Adjusted Revenue | Revenue remaining after marketplace and channel fees | A like-for-like top line across laboratories using gross and net presentations |
| Compute Contribution Margin | Revenue remaining after direct inference costs | Whether serving the model is profitable on a unit basis |
| Full Intelligence Margin | Revenue remaining after compute, distribution and workload-specific infrastructure expense | The economic value that actually stays in Layer 4 |
These metrics could become increasingly important for comparing frontier laboratories as more of them approach public markets, and they have the additional virtue of making the Cloud Tithe measurable rather than rhetorical. The difference between Marketplace Revenue and Infrastructure-Adjusted Revenue is the distribution tithe. The difference between Infrastructure-Adjusted Revenue and Compute Contribution Margin is the compute tithe. And the difference between Compute Contribution Margin and Full Intelligence Margin is the residual claim of memory, power and specialized infrastructure that is usually invisible in a laboratory’s own accounts because it is embedded in the prices charged by the cloud.
1.6 The Five-Layer Margin Cascade
This subsection introduces the recurring visual framework that organizes the remainder of the paper. Every successful AI transaction begins with a customer dollar, and that dollar is then subject to a sequence of claims as it travels downward through the stack.
Customer Dollar → Application → Model → Cloud → Chips → Energy
Not every dollar literally travels through every layer, and the cascade should not be read as a mechanical waterfall in which fixed percentages are deducted at each step. An application company that builds on a model served through a cloud marketplace pays the model company, which pays the cloud, which pays the chip vendor, which pays the memory supplier and the foundry, all of whom pay for electricity; but a vertically integrated hyperscaler may internalize several of these steps, and a laboratory that owns its datacenters converts an external claim into an internal cost. Economically, however, every successful AI transaction creates claims from several layers, and the central analytical challenge is to determine which layer possesses enough scarcity, differentiation and bargaining leverage to preserve the greatest share of the original dollar. The software era answered that question in favor of the application layer, because the layers beneath it were commoditized. The question for the AI era is whether the layers beneath the model have become scarce enough, and the model itself common enough, that the answer has changed.

Section 2: The Cloud Partner Is No Longer Just the Cloud Provider
Conventional industrial economics was built around relationships that could be named with a single word. A firm had suppliers, from whom it bought inputs; customers, to whom it sold outputs; investors, who financed it; and competitors, against whom it struggled for market share. The vocabulary assumed that these roles were occupied by different parties, and most of the analytical apparatus of strategy, from Porter’s five forces to the resource-based view of the firm, inherited that assumption. The relationships that now surround a frontier laboratory violate it comprehensively. This section examines, one at a time, the five roles that a single hyperscaler may occupy simultaneously with respect to a single laboratory, and it closes with a sixth consideration, the informational advantage that accrues to whoever collects the tithe, which may in the long run prove more consequential than any of the five.
2.1 Supplier
The most obvious relationship is infrastructure supply, and it is also the one that has grown most dramatically in scale. Frontier laboratories require enormous quantities of accelerator capacity, and that capacity is overwhelmingly supplied by a small number of cloud providers that either purchase accelerators from Nvidia and others or design their own. Amazon Web Services provides Anthropic with Trainium infrastructure, and the April 2026 agreement extends that supply across the Trainium2, Trainium3 and as-yet-unreleased Trainium4 generations together with tens of millions of Graviton processor cores.[6][14] Google supplies TPUs under an October 2025 agreement for up to one million chips and, through Broadcom, under the April 2026 agreement for approximately 3.5 gigawatts of next-generation capacity beginning in 2027.[15] Nvidia GPUs remain part of Anthropic’s diversified architecture and are the substrate of its November 2025 commitment to purchase $30 billion of capacity on Microsoft Azure.[16] Infrastructure, in other words, is no longer generic cloud hosting of the kind that a startup might rent by the hour; it is a strategic production input contracted in gigawatts and in decades, and the supplier of that input is in a position to influence the laboratory’s product roadmap, its cost structure and its geographic footprint.
2.2 Distributor
Hyperscalers possess something almost as valuable as compute, and in some respects more durable: existing enterprise relationships. Thousands of companies already have AWS accounts, Azure commitments and Google Cloud contracts, and with those accounts come security approvals, identity systems, billing relationships, procurement agreements and, crucially, committed cloud spending that enterprise buyers are often eager to draw down against pre-approved budgets. Selling Claude through those platforms allows Anthropic to enter environments where a separate vendor approval process might otherwise take months, and it allows the enterprise to apply its existing cloud commitment toward model consumption rather than negotiating a new contract with an unfamiliar counterparty. Anthropic itself has argued that this gives it market penetration that would be difficult for any single organization to reproduce independently, and the company’s own announcement in April 2026 noted that more than 100,000 customers were accessing Claude through Amazon Bedrock alone.[1][17]
That distribution advantage helps explain why a cloud marketplace can command a meaningful share of revenue, and it also explains why the share rose rather than fell as Anthropic grew. Reuters reported that sales through Amazon and Google rose from 11 percent of Anthropic’s revenue in 2023 to 32 percent in 2024 and 47 percent in 2025, and that the platforms were responsible for collecting 60 percent of the $909 million in customer bills outstanding at the end of 2025, up from 42 percent a year earlier.[1] A sales channel that grows faster than the business it serves is not a convenience; it is becoming part of the business’s infrastructure, and the laboratory’s own warning that disputes or delays in that collection pipeline could affect its cash flow, even though it contracts directly with the customers, confirms that the dependence has become operational as well as commercial.[1]
2.3 Investor
The relationship becomes more unusual when the supplier is also financing the customer. Amazon’s cumulative investment in Anthropic reached $8 billion across 2023 and 2024, rose to $13 billion with the $5 billion tranche announced on April 20, 2026, and could reach $33 billion if the additional $20 billion of milestone-based capital is drawn.[6][14] Google has also invested substantial capital, and in November 2025 Microsoft and Nvidia announced plans to invest up to $15 billion in Anthropic alongside the company’s $30 billion Azure commitment.[16] The money helps Anthropic scale. Anthropic then uses enormous amounts of cloud infrastructure, much of it purchased from the same investors. The investors, in turn, record gains on their stakes as the laboratory’s valuation rises: Amazon’s second-quarter 2026 net income of $62.6 billion included non-operating pre-tax other income of $53.4 billion, which the company said arose primarily from its investments in Anthropic, and Alphabet’s first-quarter 2026 other income reflected a net gain of $37.7 billion, primarily from unrealized gains on non-marketable equity securities.[18][19]
None of this automatically makes the arrangement uneconomic or improper, and it is worth resisting the temptation to treat circularity as a synonym for fraud. Vendor financing has a long and respectable history in capital-intensive industries, from railway equipment to aircraft to telecommunications switches. But it does create a circular structure that is fundamentally different from an ordinary vendor relationship, and it means that the valuation of the laboratory, the revenue of the cloud provider and the capital available for the next round of infrastructure are linked by feedback loops that run in both directions. The International Monetary Fund identified exactly this feature in its 2026 annual report, warning that within the AI stack, arrangements in which a small group of firms simultaneously act as each other’s customers, investors and financiers increase the risk that problems in one firm cascade to others.[20] Forbes columnist Jon Markman put the strategic logic of the Amazon–Anthropic arrangement more bluntly.
Amazon paid $33 billion to guarantee that when the compute comes online, Anthropic runs on it.
— Jon Markman, Forbes [21]
2.4 Competitor
Amazon, Google and Microsoft are not neutral infrastructure utilities in the manner of an electricity grid or a toll road. Each operates a significant artificial-intelligence business of its own. Google develops Gemini and sells it through the same Vertex AI platform that distributes Claude. Amazon develops its own model families and custom silicon, and in the second quarter of 2026 it began hosting OpenAI models on AWS as well.[22] Microsoft develops AI products across Azure and its software ecosystem, and by April 2026 it was publicly previewing its own home-grown models even as it remained OpenAI’s primary cloud partner.[23] The cloud provider can therefore simultaneously help distribute a frontier laboratory’s technology and compete with that technology, sometimes within the same product catalogue and sometimes within the same customer conversation. Anthropic’s prospectus acknowledged this directly, noting, according to Reuters, that its reliance on a limited number of partners and suppliers creates complex dynamics that could give rise to conflicts of interest and could adversely affect its access to compute.[1]
2.5 Customer
The geometry becomes stranger still because cloud companies and their affiliates can themselves consume AI models, and Anthropic’s filing noted that the cloud companies are also its customers.[1] A hyperscaler that embeds Claude in its own productivity tools, its own coding assistants or its own customer-service systems is paying the laboratory for intelligence while simultaneously collecting from the laboratory for infrastructure and distribution, and the net flow between the two companies becomes a function of several contracts rather than one. A single company can therefore be, at the same time and with respect to the same counterparty, an investor, a supplier, a distributor, a customer and a competitor.
Investor → Supplier → Distributor → Customer → Competitor
Traditional industrial economics rarely produced all five relationships between the same two companies, and when it did, as in the case of Japanese keiretsu or the Korean chaebol, it treated the result as a distinctive and somewhat exotic institutional form worthy of its own literature. Frontier AI increasingly produces it as a default, and the implication is that the strategic analysis of a laboratory cannot be performed by examining its competitors and its suppliers separately, because they are frequently the same firms.
2.6 Infrastructure Intelligence
This raises a deeper strategic issue that is easy to overlook because it does not appear on any income statement. The institution that collects the tithe also observes the transactions on which the tithe is levied, and in an industry whose central scarce resource is forward visibility into demand, that observation may be worth more than the fee itself. Cloud platforms potentially observe enterprise purchasing patterns, workload growth, regional demand, model consumption by sector and by use case, infrastructure requirements, pricing structures and emerging capacity shortages. Anthropic’s filing noted, according to Reuters, that its cloud relationships provide its partners with visibility into its pricing and commercial terms, and that this visibility could influence the partners’ decisions about compute allocation and about how aggressively to sell Anthropic’s products.[1]
That information is strategically valuable in at least three ways. It informs the cloud provider’s own model development, because the provider can see which capabilities enterprises are actually paying for. It informs the provider’s capital allocation, because the provider can see where demand is forming before that demand appears in anyone’s public filings. And it informs the provider’s negotiating position with the laboratory itself, because the provider knows the laboratory’s pricing, its customer concentration and its growth trajectory in close to real time. The company collecting the Cloud Tithe may therefore also learn where tomorrow’s intelligence demand is forming, and it may act on that knowledge in markets where the laboratory is a competitor. This is the sense in which distribution is becoming infrastructure, a theme to which the paper returns in its concluding pillars.

Section 3: Anthropic as the First Great Cloud-Tithe Case Study
Every industrial transformation acquires, at some point, a canonical case that converts an abstract thesis into a set of numbers that can be argued over, and the Anthropic prospectus is likely to serve that function for the economics of frontier models. It offers a rare opportunity because an IPO process has exposed economics that are normally hidden inside private contracts, and because the company’s trajectory, from roughly $386 million of revenue in 2024 to nearly $4.6 billion in 2025 and to a reported $11.5 billion in the single quarter ending June 2026, compresses into three years a scaling process that took the previous generation of platform companies a decade.[5][24] This section walks through the case in six steps: the 47 percent distribution figure, the sixteen-cent marketplace claim, the compute beneath the marketplace, the gigawatt-scale commitments to Amazon and Google, the multicloud strategy as a bargaining architecture, and the way in which the IPO process itself converts a private arrangement into a public variable.
3.1 The 47 Percent Distribution Number
The single most important chart in this paper is the three-year progression in the share of Anthropic’s revenue that flows through the Amazon and Google marketplaces, because it overturns a comfortable assumption about the relationship between scale and independence.
| Year | Marketplace Share of Revenue | Approximate Total Revenue | Interpretation |
| 2023 | 11% | Low hundreds of millions | Marketplace is a supplementary channel |
| 2024 | 32% | ~$386 million | Marketplace becomes a principal channel |
| 2025 | 47% | ~$4.59 billion ($2.16 billion via marketplaces) | Marketplace approaches half of all revenue |
The progression demonstrates that cloud dependence can increase even as a frontier laboratory becomes larger, more sophisticated and more commercially successful. Scale does not automatically produce independence. Sometimes scale increases dependence, because the amount of infrastructure and distribution required to serve a rapidly growing enterprise customer base grows even faster than the laboratory’s own capacity to build sales teams, billing systems and compliance machinery. The receivables data reinforce the point: the share of outstanding customer bills collected by third-party platforms rose from 42 percent at the end of 2024 to 60 percent at the end of 2025, which means that the laboratory’s cash conversion cycle has become partly a function of its partners’ collection processes.[1] An investor who assumed that a $65 billion run-rate business would naturally have reduced its channel dependence relative to a $1 billion run-rate business would, on the evidence of this filing, have assumed wrongly.
3.2 The Sixteen-Cent Marketplace Claim
The $351 million of estimated distribution fees on roughly $2.16 billion of marketplace revenue gives the paper its economic anecdote, and the figure deserves careful handling precisely because it is so quotable. It should not be universalized into an assumption that every cloud marketplace charges exactly sixteen percent, that the rate is fixed across contract sizes, or that it applies to revenue flowing through Microsoft Azure, which Reuters did not include in the 47 percent calculation. Reuters itself described the sixteen-cent figure as the product of its own analysis of the filing rather than as a number Anthropic disclosed directly.[1] Instead, the figure should be used as empirical evidence that a substantial recurring infrastructure-distribution claim can exist at the frontier of the industry, at a laboratory with a $965 billion private valuation and the strongest bargaining position of any independent model company.[25]
The question that follows is whether the claim scales with the business. If Claude becomes ten times larger economically, does the absolute Cloud Tithe become ten times larger, or does Anthropic gain enough bargaining leverage to renegotiate the rate downward? The honest answer is that the filing does not tell us, and that the answer will depend on the relative scarcity of what each side brings to the table. If enterprise distribution remains the binding constraint, the rate may hold or even rise. If the laboratory’s model becomes the thing enterprises demand by name, so that the marketplace is merely the checkout counter rather than the reason for the purchase, the rate should fall, as it did in the comparable case of mobile application stores once developers acquired enough collective leverage to force concessions. The sixteen cents is therefore best understood not as a constant but as the opening reading on an instrument that investors will now be able to monitor filing by filing.
3.3 Compute Beneath the Marketplace
The distribution fee is only the visible layer. Beneath it lies the far larger compute claim, and the two together describe a dependence that is multidimensional rather than linear. Reuters reported approximately $7.33 billion of compute and infrastructure expense during 2025, up roughly 190 percent from the prior year and accounting for about 58 percent of total operating expenses.[5] That means the laboratory relies on cloud companies to help it accomplish at least five distinct things, each of which could in principle be contracted separately but which are in practice bundled into a small number of very large relationships.
- Create the intelligence, through training clusters measured in hundreds of thousands of accelerators.
- Host the intelligence, through globally distributed inference capacity.
- Distribute the intelligence, through enterprise marketplaces with existing procurement relationships.
- Bill for the intelligence, through collection systems that now handle the majority of outstanding receivables.
- Finance the infrastructure producing the intelligence, through equity investments and milestone-based capital that are themselves contingent on the laboratory’s purchase commitments.
Cloud Tithe therefore describes an ecosystem rather than one accounting line. A laboratory that reduced its marketplace fee to zero by selling exclusively through its own channel would still face the compute claim; a laboratory that owned its datacenters would still face the chip and memory claims; and a laboratory that designed its own chips would still face the foundry, packaging and energy claims. The tithe migrates; it does not disappear, and the remainder of this section examines how large the migration has become.
3.4 Project Rainier and the Gigawatt Scale
On April 20, 2026, Anthropic and Amazon announced that their collaboration could expand by as much as five gigawatts of computing capacity, and that Anthropic would commit more than $100 billion over ten years to AWS technologies, including current and future generations of Trainium and tens of millions of Graviton cores.[14] The announcement built on Project Rainier, the Trainium cluster on which Anthropic runs its primary training workloads using more than one million Trainium2 chips, with roughly one gigawatt of Trainium2 and Trainium3 capacity expected online by the end of 2026.[17] Amazon’s chief executive Andy Jassy framed the agreement as the product of several years of joint work on custom silicon.
…reflects the progress we’ve made together on custom silicon.
— Andy Jassy, President and CEO, Amazon [17]
At this scale, frontier AI laboratories begin to resemble industrial manufacturers contracting for production capacity rather than software companies renting servers. Five gigawatts is roughly the output of five large nuclear reactors, and a commitment of that size cannot be relocated, renegotiated or abandoned on the timescales that software economics assumed. A laboratory can no longer switch infrastructure providers as casually as an ordinary startup changes hosting services, because the provider has built, or is building, physical plant specifically for that laboratory’s workloads, and because the laboratory’s own software has been optimized for that provider’s silicon. Gigawatt commitments create physical inertia, and physical inertia is bargaining power for whoever owns the plant. The circular structure of the agreement, in which $25 billion of prospective equity investment accompanies $100 billion of prospective purchase commitments, is the financial expression of that inertia: each side has made the other’s success a precondition of its own.
3.5 Multicloud as Bargaining Architecture
Anthropic’s response to this dependence is not pure vertical integration, at least not yet. It is diversification, and the diversification is deliberate enough to be understood as a strategy rather than an accident of opportunistic contracting. The company trains and serves Claude on AWS Trainium, Google TPUs and Nvidia GPUs; it distributes through Amazon Bedrock, Google Cloud Vertex AI and Microsoft Azure Foundry; and it has described itself as the only frontier model available on all three of the world’s largest cloud platforms.[26] On April 6, 2026, Broadcom disclosed in a securities filing that Anthropic would, beginning in 2027, access approximately 3.5 gigawatts of next-generation TPU-based capacity through Broadcom as part of a larger multi-gigawatt commitment, and that Broadcom and Google had separately entered long-term agreements covering future TPU generations and networking components through 2031.[15] Anthropic’s chief financial officer Krishna Rao described the arrangement in terms that emphasized discipline rather than scale.
…a continuation of our disciplined approach to scaling infrastructure.
— Krishna Rao, Chief Financial Officer, Anthropic [7]
That strategy may serve several purposes simultaneously: resilience against the failure or capacity shortfall of any single provider, access to scarce compute wherever it happens to be available, geographic reach into regions where one provider is stronger than another, enterprise distribution through three marketplaces rather than one, and negotiating leverage with each provider derived from the credible existence of the others. Anthropic describes its diversified hardware approach as allowing workloads to be matched to the chips best suited for them while strengthening resilience for customers.[7] Multicloud therefore becomes more than a technical architecture. It becomes a bargaining architecture, in which the cost of maintaining portability across three accelerator families is the price the laboratory pays to prevent any one of them from capturing the full tithe. Whether that price is lower than the tithe it prevents is one of the central empirical questions that future filings will answer.
3.6 The IPO Makes the Tithe Visible
Private-market investors may tolerate extraordinarily complex relationships because the overriding objective during the scaling phase is growth, and because the investors are frequently the same companies whose relationships are being tolerated. Public markets impose different questions, and they impose them repeatedly, quarter after quarter, in a format that permits comparison across companies and across time. The Anthropic prospectus has already begun to establish the vocabulary of those questions. Investors will increasingly ask what the normalized gross margin is once marketplace fees and compute are both deducted; what percentage of revenue depends on cloud marketplaces and what percentage flows back to those partners; what portion of infrastructure spending is fixed versus variable; how much compute has been contractually committed and whether those obligations can be repriced; how dependent the company is on individual accelerator architectures; and what happens if model prices decline faster than inference costs. They will also ask about customer concentration, because the filing disclosed that two unnamed customers each accounted for roughly twelve percent of 2025 revenue and that many of the largest customers are not bound by long-term contracts.[1]
The IPO process has also provided the first set of answers. In August 2026 Anthropic told investors that its preliminary second-quarter revenue exceeded $11.5 billion, up from $787 million a year earlier and $4.73 billion in the first quarter, and that it had recorded positive adjusted operating income for the first time.[24] The annualized run rate reached $65 billion at the end of July.[10] An investor quoted by Axios attributed part of that performance to the laboratory’s relative efficiency in converting compute into revenue.
Anthropic was much more token efficient than OpenAI but OAI has closed some of the gap.
— Gavin Baker, Managing Partner, Atreides Management [27]
The comment is significant for this paper because token efficiency is, in the framework developed here, a direct determinant of the compute tithe: a laboratory that produces more revenue per accelerator-hour surrenders a smaller share of each dollar to the layer beneath it. The Anthropic IPO could therefore help establish a new vocabulary for valuing frontier-model companies, one in which the relevant comparisons are not only growth rates and model benchmarks but the share of each customer dollar that survives the journey down the stack and the efficiency with which the laboratory converts its scarcest input into its most valuable output.

Section 4: The Other Side of the Ledger — What the Earnings of 2026 Reveal About Who Collects
A tithe has two parties, and a paper that examined only the laboratory’s side of the transaction would be incomplete in a way that distorts the analysis, because the infrastructure layer’s own financial statements reveal whether the claim it levies is actually being collected, at what margin, and with what degree of dependence on the very laboratories that pay it. The second quarter of calendar 2026, together with Nvidia’s quarter ending in July and Oracle’s quarter ending in August, provides the most complete set of such statements yet available, and this section reads them as the counterparty’s ledger. The exercise reveals three things. The first is that the infrastructure layer is collecting extraordinary and accelerating revenue at margins that would have been considered implausible for a capital-intensive business a decade ago. The second is that the collection is itself financed by capital expenditure and borrowing on a scale that makes the hyperscalers dependent on the continued growth of the laboratories whose revenue they tithe. The third is that the scarcity which gives the infrastructure layer its bargaining power is migrating downward, into memory and power, where the hyperscalers are themselves tithe-payers rather than collectors.
4.1 The Hyperscaler Quarter
The three largest cloud providers reported their June-quarter results within eight days of one another in late July 2026, and the results, summarized in the table below, describe an infrastructure layer in the midst of its fastest expansion since the early years of public cloud.
| Company (Quarter) | Cloud Revenue | Growth | Cloud Operating Income / Margin | Backlog or RPO | Capital Expenditure |
| Amazon / AWS (Q2 2026, reported July 30) | $42.2 billion | +37% (fastest in 18 quarters) | $16.6 billion / 39.4% | Not separately disclosed | ~$54 billion in quarter; ~$220 billion 2026 plan |
| Alphabet / Google Cloud (Q2 2026, reported July 22) | $24.8 billion | +82% | $8.8 billion / 35.6% | $514 billion cloud backlog (+$50 billion sequential) | $44.9 billion in quarter; $195–205 billion 2026 guidance |
| Microsoft / Azure (FY26 Q4, reported July 29) | Microsoft Cloud $59.3 billion; Azure >$100 billion for FY26 | Azure +43% in quarter; +41% for fiscal year | Not separately disclosed for Azure | $678 billion commercial RPO (+84%) | $41 billion incl. finance leases (+69%) |
Sources: company earnings releases, call transcripts and SEC filings.[18][22][28][29][30][31][32][33]
Amazon’s results are the most directly relevant to the Anthropic case, because Amazon is Anthropic’s primary cloud and training partner. AWS revenue of $42.2 billion grew 36.7 percent year over year, which the company described as its fastest growth in eighteen quarters, and AWS operating income of $16.6 billion represented a 39.4 percent operating margin, up from 32.9 percent a year earlier.[18][22] AWS supplied roughly 21 percent of Amazon’s consolidated revenue but roughly 60 percent of its operating income, and the company said that its AI and custom-chip businesses had each surpassed a $25 billion annualized revenue run rate.[22][34] Management raised its 2026 capital spending plan to approximately $220 billion, most of it directed at AWS and generative AI, and cash capital expenditures in the quarter alone were roughly $53 billion.[28] The same quarter’s net income of $62.6 billion included $53.4 billion of non-operating gains arising primarily from Amazon’s investments in Anthropic, which means that the single largest contributor to Amazon’s reported profit in the quarter was the appreciation of its stake in the laboratory to which it supplies infrastructure, from which it collects marketplace fees, and with which it competes.[18] The circle described in Section 2 is not a metaphor; it is visible in a single income statement.
Alphabet’s results illustrate a different facet of the same system. Google Cloud revenue grew 82 percent to $24.8 billion, cloud operating income more than tripled to $8.8 billion, and the cloud backlog reached $514 billion, having increased by more than $50 billion in a single quarter, with just over half expected to be recognized as revenue within twenty-four months.[29][30] In the same quarter Alphabet began, for the first time, to recognize revenue from the sale of TPU systems delivered to customer datacenters, and its chief financial officer confirmed that those sales are included in the cloud backlog.[29][35]
…the TPU system sales are reflected in that backlog.
— Anat Ashkenazi, Chief Financial Officer, Alphabet [29]
This is significant for the Five-Layer framework because it marks the moment at which a Layer 3 company began selling Layer 2 hardware directly, converting what had been an internal transfer into an external revenue line and thereby extending its tithe-collecting reach into the accelerator market itself. Alphabet raised its 2026 capital expenditure guidance to between $195 billion and $205 billion, and in June 2026 it announced $30 billion of equity and mandatory-convertible issuance together with a $40 billion at-the-market program, stating that the proceeds would fund capital expenditures to scale AI infrastructure and global compute.[30][36] A company that for two decades financed its growth entirely from operating cash flow was now raising equity to build datacenters, which is the clearest possible evidence that the capital intensity of the infrastructure layer has outrun even the largest internal cash engines in the history of commerce.
Microsoft’s fiscal fourth quarter completed the picture. Azure and other cloud services grew 43 percent, Azure revenue exceeded $100 billion for the fiscal year for the first time, Microsoft Cloud revenue reached $59.3 billion in the quarter and $214 billion for the year, and commercial remaining performance obligations rose 84 percent to $678 billion.[31][32] Management emphasized that all of the sequential growth in that backlog came from customers outside the frontier-model companies, and that RPO excluding OpenAI grew 25 percent, a disclosure whose very necessity reveals how large the frontier laboratories have become as a share of hyperscaler contracted revenue: in January 2026 Microsoft had disclosed that roughly 45 percent of its then-$625 billion commercial RPO was tied to OpenAI, and its fiscal 2026 annual report later revealed approximately $24.1 billion of revenue from OpenAI, about seven percent of the company’s total.[33][37] The company’s commentary on capacity was unambiguous.
Customer demand continues to exceed available capacity.
— Microsoft FY2026 Q4 Earnings Call [32]
When the collector of a tithe reports that it cannot supply enough of the thing on which the tithe is levied, the bargaining power in the relationship is not in doubt, at least for the present.
4.2 The Chip Layer and the Compute-Is-Revenue Thesis
Nvidia’s quarter ending July 26, 2026 established the scale of the Layer 2 claim with numbers that defy easy comparison. Revenue of $96.2 billion rose 106 percent from a year earlier; datacenter revenue of $89.0 billion rose 117 percent; GAAP gross margin was 75.0 percent; and the company guided to $108 billion of revenue for the following quarter while assuming no datacenter compute revenue from China.[12][38] In the prior quarter the company had disclosed that hyperscalers represented approximately half of datacenter revenue, with the remainder coming from AI clouds, enterprises, industrial customers and sovereign buyers, a diversification that it cited as evidence that the buildout was no longer dependent on a single laboratory.[39] For the purposes of this paper, the relevant observation is that a 75 percent gross margin at the chip layer, sustained across a revenue base approaching $400 billion annualized, represents a claim on the AI economy that is collected before any hyperscaler margin and long before any laboratory margin, and that is embedded in the price of every accelerator-hour that a laboratory rents. The hyperscalers’ own custom silicon programs, Trainium and TPU foremost among them, are in this light best understood as attempts by Layer 3 to reduce the tithe it pays to Layer 2, exactly as the laboratories’ multicloud strategies are attempts by Layer 4 to reduce the tithe it pays to Layer 3. Every layer is simultaneously a collector and a payer, and the pattern repeats all the way down.
4.3 Infrastructure Pluralism: Oracle and the Neoclouds
Oracle’s quarter ending August 31, 2026 demonstrated that the tithe need not be collected by the three traditional hyperscalers alone. Total revenue rose 30 percent to a record $19.3 billion, cloud infrastructure revenue rose 121 percent to $7.4 billion, and remaining performance obligations reached $664 billion, up $209 billion from a year earlier, with the company expecting to recognize approximately 13 percent of that figure over the following twelve months, 37 percent over months thirteen through thirty-six and 34 percent over months thirty-seven through sixty.[40][41] During the quarter the company received $11.4 billion of customer prepayments that included a significant financing component, a mechanism through which the customer, in effect, finances the supplier’s construction of the capacity it will later consume.[41] Oracle’s own description of the demand environment echoed Microsoft’s.
Customer demand for AI Cloud Training and Inferencing Services continues to grow faster than supply.
— Oracle Q1 FY2027 Earnings Release [40]
The price of that collection, however, was visible in the same filing. Capital expenditure in the quarter was approximately $28.5 billion, free cash flow was negative by roughly $5.4 billion, and the company projected full-year capital spending of $90 billion to $95 billion against a revenue base of at least $90 billion.[42] An infrastructure company whose annual capital expenditure equals its annual revenue is not collecting a tithe in the leisurely manner of a landed estate; it is borrowing against future tithes to build the land. The largest single component of Oracle’s backlog is widely reported to be its approximately $300 billion, five-year agreement with OpenAI covering up to 4.5 gigawatts of capacity beginning in 2027, which means that the collector’s balance sheet is now as exposed to the laboratory’s success as the laboratory is exposed to the collector’s capacity.[43]
CoreWeave, the largest of the specialized AI clouds, offered the purest illustration of this exposure. Second-quarter 2026 revenue of $2.58 billion rose 112 percent, the revenue backlog reached $104 billion as of June 30 and approximately $129 billion by the August 11 earnings date after more than $25 billion of new commitments, including new business with Anthropic and Meta, and the company ended the quarter with 1.5 gigawatts of active power.[44][45] Yet net loss widened to $626 million, driven principally by roughly $640 million of quarterly interest expense on approximately $35 billion of debt incurred largely to purchase Nvidia GPUs, and capital expenditure in the quarter was $9.4 billion.[44][46] The neocloud model, in which GPU-collateralized debt finances capacity that is leased to laboratories under multi-year contracts, is the clearest case of a tithe collector whose own cost of capital consumes most of what it collects, and it is also the mechanism through which the infrastructure claim is divided among lenders, landlords and operators rather than captured by a single hyperscaler. Specialized infrastructure does not eliminate the Cloud Tithe; it changes who receives it and adds a layer of financial intermediation on top.
4.4 The Scarcity Beneath the Scarcity: Memory and Power
The hyperscalers’ bargaining power over the laboratories derives from scarcity, but scarcity has a floor beneath it, and in 2026 that floor became visible in two places. The first is memory. High-bandwidth memory, the stacked DRAM that sits alongside every frontier accelerator, is produced in volume by only three companies, SK hynix, Samsung and Micron, and all three reported that their HBM capacity for 2026 was fully allocated under multi-year agreements, with several reports indicating that DRAM and HBM supply was committed through 2027 as well.[47][48][49] Because producing one bit of HBM consumes roughly three times the wafer capacity of standard DRAM, the reallocation of fabs toward HBM created a structural shortage in conventional memory, and contract DRAM prices rose by more than ninety percent in the first quarter of 2026 alone.[47][48] Samsung’s head of global marketing warned publicly that memory shortages would affect pricing industry-wide, and the consequence for the Five-Layer framework is that Layer 3, which collects a tithe from Layer 4, is itself paying a sharply rising tithe to a Layer 2 oligopoly whose capacity cannot be expanded on anything less than a multi-year horizon.[47]
The second floor is power. The International Energy Agency reported in April 2026 that global data-centre electricity demand grew 17 percent in 2025 while demand from AI-focused data centres grew 50 percent, both far outpacing the 3 percent growth in global electricity demand, and it projected that data-centre consumption would roughly double from 485 terawatt-hours in 2025 to 950 terawatt-hours in 2030, with AI-focused consumption tripling over the same period.[50][51] The agency observed that capital investment by five large technology companies in data centres had surged past $400 billion in 2025 and was set to rise by a further 75 percent in 2026, and it drew attention to the engineering limits that the buildout was approaching.[51]
AI is pushing data centre power density to the limits of today’s technologies.
— International Energy Agency, Key Questions on Energy and AI (April 2026) [50]
The policy response in the United States has been to treat the energy constraint as a matter of national competitiveness. The White House’s July 2025 AI Action Plan, organized around three pillars of innovation, infrastructure and international security, called for streamlined permitting for datacenters, semiconductor facilities and energy infrastructure, for the use of federal lands for datacenter construction, and for a grid developed to match the pace of AI innovation, and it was accompanied by an executive order on accelerating federal permitting of datacenter infrastructure.[52] That the federal government regards the Layer 1 constraint as binding enough to warrant a dedicated permitting regime is itself evidence that energy has become the deepest and least elastic claim in the cascade. The infrastructure layer that collects the Cloud Tithe is, in the end, a tenant of the grid, and the grid’s own scarcity will set the floor beneath every margin above it.
4.5 Financing the Collection
The final observation from the counterparty’s ledger concerns how the collection is financed, because a tithe collector that borrows to build is exposed in ways that a tithe collector that merely owns is not. The five largest hyperscalers issued $121 billion of United States investment-grade bonds in 2025, including the largest non-acquisition high-grade deal ever recorded, and analysts at Bank of America projected that the group would borrow roughly $140 billion annually over the following three years, an amount that could make the hyperscalers among the largest issuers in the entire investment-grade index.[53] Alphabet’s June 2026 equity raise, Oracle’s negative free cash flow, CoreWeave’s $35 billion of GPU-backed debt and the proliferation of special-purpose vehicles and private-credit facilities for datacenter construction together describe a system in which the infrastructure layer’s claim on the laboratories is matched by the capital markets’ claim on the infrastructure layer. Two independent working papers posted to the Social Science Research Network in 2026 mapped these interlocking commitments at more than $800 billion and $1.4 trillion respectively, and the author of the second described the phenomenon in terms that the IMF would echo.
…the same pool of capital rotates continuously among a small group of companies.
— Rahil Solanki, The AI Circular Economy (SSRN, April 2026) [54]
The point for this paper is not that circular financing is necessarily unstable, but that it changes the character of the tithe. A claim that is financed by debt must be collected on schedule, and a collector that must collect on schedule has less flexibility to forgive, defer or renegotiate than a collector that owns its capacity outright. The hyperscalers’ growing reliance on debt and equity markets to fund the buildout therefore tends, at the margin, to make the Cloud Tithe stickier rather than softer, because the infrastructure layer has itself promised the proceeds to someone else.

Section 5: Four Architectures for Capturing Artificial-Intelligence Margin
Having examined both sides of the ledger, the paper can now step back and ask how the relationships between model laboratories and infrastructure providers are actually organized, because the Cloud Tithe is not levied through a single contractual form but through several, and the form determines how the tithe can be renegotiated. This section examines the four architectures that had crystallized by the autumn of 2026: the deep interdependence of Amazon and Anthropic, the strategic diversification that characterizes Google’s relationship with the same laboratory, the explicit revenue-sharing structure that binds OpenAI to Microsoft, and the infrastructure pluralism represented by Oracle, CoreWeave and the specialized clouds. It closes by considering the vertically integrated hyperscaler as a fifth case in which the tithe is internalized rather than paid, and by proposing a four-part typology of the structures toward which the industry appears to be converging.
5.1 Amazon–Anthropic: Deep Infrastructure Interdependence
The Amazon–Anthropic relationship represents perhaps the clearest version of infrastructure interdependence in the industry. Amazon supplies capital, in the form of $13 billion invested to date and up to $20 billion more tied to commercial milestones. AWS supplies cloud capacity, in the form of Project Rainier and the five-gigawatt envelope agreed in April 2026. Trainium supplies accelerators across three current and future generations. Bedrock supplies distribution to more than 100,000 customers. And Anthropic supplies a frontier model that increases the attractiveness of the entire AWS AI ecosystem to enterprises that might otherwise have defaulted to a competitor’s cloud.[6][14][17] Neither side is simply customer or supplier. The relationship creates mutual dependence of a kind that economists would describe as bilateral monopoly with relationship-specific investment: Amazon has built silicon and datacenters whose value is highest when Anthropic uses them, and Anthropic has optimized its models for silicon that only Amazon supplies. In such relationships the division of surplus is determined not by market prices, which do not exist for a bespoke five-gigawatt Trainium cluster, but by bargaining, and the sixteen-cent marketplace fee is one visible outcome of that bargaining. The $53.4 billion gain that Amazon recorded on its Anthropic stake in a single quarter is another, and it suggests that the largest return Amazon has so far earned from the relationship is not the tithe at all but the equity.
5.2 Google–Anthropic: Strategic Diversification
Google occupies a similarly multidimensional position, as investor, cloud provider, TPU supplier, distribution platform through Vertex AI, and developer of Gemini, the model that competes most directly with Claude in the enterprise market. Anthropic has nevertheless expanded its Google and Broadcom compute arrangements, from the October 2025 agreement for up to one million TPUs to the April 2026 agreement for approximately 3.5 gigawatts beginning in 2027, while keeping Amazon as its primary cloud provider and training partner.[15][26] Analysts at Mizuho estimated after the April announcement that Broadcom’s prospective revenue from Anthropic could reach $21 billion in 2026 and $42 billion in 2027, which, if accurate, would make a single laboratory one of the largest customers of a chip designer whose primary customer is a different hyperscaler.[55] This illustrates an important distinction that is easy to lose amid the headline numbers: dependence on infrastructure does not necessarily mean dependence on one infrastructure company. The frontier laboratory may attempt to convert supplier competition into bargaining power, and the existence of a credible second source for gigawatt-scale accelerator capacity is precisely what prevents the first source from setting the tithe unilaterally.
5.3 Microsoft–OpenAI: Revenue Sharing as Structural Architecture
Microsoft and OpenAI provide the most instructive comparative case, because their relationship expresses the Cloud Tithe not as a marketplace fee but as an explicit percentage of the laboratory’s revenue, and because that relationship has been restructured at least three times as OpenAI’s infrastructure requirements, valuation and strategic options expanded. Under the arrangement in force through 2025, OpenAI shared roughly twenty percent of its revenue with Microsoft, and the laboratory told investors that it expected to reduce the share paid to all of its commercial partners to roughly ten percent by the end of the decade.[56] On April 27, 2026, the two companies announced amended terms under which Microsoft remains OpenAI’s primary cloud partner and OpenAI products ship first on Azure unless Microsoft cannot or chooses not to support them, while OpenAI gained the freedom to serve all of its products across any cloud provider; Microsoft’s license to OpenAI intellectual property through 2032 became non-exclusive; Microsoft ceased paying a revenue share to OpenAI; and OpenAI’s revenue-share payments to Microsoft were made independent of OpenAI’s technological progress, eliminating the previous clause tied to artificial general intelligence.[57][58] The critical sentence in Microsoft’s own announcement concerned the terms on which those payments would continue.
…at the same percentage but subject to a total cap.
— Microsoft, The Next Phase of the Microsoft–OpenAI Partnership (April 27, 2026) [57]
This matters enormously for the Cloud Tithe thesis in two ways. First, it demonstrates that recurring revenue sharing is not peculiar to Anthropic’s marketplace arrangements; the other leading laboratory pays a structurally similar claim through a different contractual mechanism, and the two mechanisms should be analyzed together rather than treated as unrelated. Second, the introduction of a total cap is the first documented instance of a frontier laboratory successfully converting an uncapped proportional tithe into a bounded one, and it was achieved not by threatening to leave the primary cloud but by acquiring credible alternatives: by April 2026 OpenAI had committed to approximately $300 billion of Oracle capacity, roughly $138 billion of AWS capacity including two gigawatts of Trainium, and more than $22 billion of CoreWeave capacity, and Amazon had committed up to $50 billion of investment.[59][60] The cap on the Microsoft tithe was, in effect, purchased with commitments to other collectors. The tithe did not disappear; it was redistributed, and the redistribution happened to favor the laboratory because several collectors were competing for the same payer.
5.4 Infrastructure Pluralism: Oracle, CoreWeave and Specialized Compute
The future may not belong exclusively to the three traditional hyperscalers, and the evidence of Section 4 suggests that it already does not. Oracle, CoreWeave, specialized GPU clouds such as Nebius and the enormous dedicated datacenter developers that have emerged around the Stargate program provide alternative infrastructure, and their growth gives model companies additional suppliers and therefore additional negotiating leverage. Nvidia’s August 2026 results noted that its Vera Rubin platform was ramping into production at CoreWeave, Google Cloud, Microsoft Azure, Oracle Cloud Infrastructure and Nebius simultaneously, a list that would have contained two or three names five years earlier.[61] But specialized infrastructure does not eliminate the Cloud Tithe. It may merely change who receives it. Instead of AWS collecting the infrastructure margin, a combination of GPU lessors, datacenter operators, private-credit financiers, utilities and dedicated cloud providers may divide the same economic claim among themselves, and the division may add intermediation costs, in the form of interest expense and developer margins, that a vertically integrated hyperscaler would have avoided. CoreWeave’s $640 million of quarterly interest expense is a tithe paid by the collector to its own financiers, and it must ultimately be recovered from the laboratories that lease its capacity.
5.5 Vertical Hyperscalers
Google represents yet another architecture, because it can operate almost every major layer internally, from energy contracting through datacenters, TPUs, Google Cloud and Gemini to the applications in which Gemini is embedded. Meta increasingly follows a related path, building its own datacenters at enormous scale, designing its own silicon and training its own models for deployment in its own products. Companies operating multiple layers may transfer economic value internally rather than paying an external tithe, and their accounting looks different as a result: Google does not record a marketplace fee for selling Gemini through Vertex AI, and Meta does not pay a cloud provider for the inference that powers its recommendation systems.
Energy contracting ↓ Datacenters ↓ TPUs ↓ Google Cloud ↓ Gemini models ↓ Applications
But the infrastructure cost does not disappear merely because it is internalized, and the question becomes whether vertical integration produces lower total cost, greater strategic control, or merely shifts margins between internal business units in a way that flatters one segment at the expense of another. Alphabet’s decision in 2026 to begin selling TPU systems externally suggests that even the most vertically integrated participant has concluded that its Layer 2 capability is more valuable as a product sold to others than as an input consumed only by itself, which is to say that the vertical hyperscaler is now choosing to collect a tithe from the market rather than merely to avoid paying one.
5.6 The Four Emerging Models
By 2027 to 2030, frontier AI appears likely to organize around four broad structures, and the paper proposes the following typology, which should be read as a set of positions along a continuum rather than as fixed categories.
| Model | Name | Description | Current Exemplar | Form the Tithe Takes |
| Model A | Hyperscaler Integration | The company owns infrastructure, models and applications | Google (Gemini), Meta | Internal transfer pricing; no external fee |
| Model B | Strategic Interdependence | An independent laboratory deeply linked to one primary cloud provider through capital, silicon and distribution | Anthropic–Amazon; OpenAI–Microsoft (through 2025) | Marketplace fees, revenue share, purchase commitments |
| Model C | Multicloud Bargaining | The laboratory deliberately spreads workloads and distribution across competing providers | Anthropic (AWS, Google, Azure); OpenAI (Azure, Oracle, AWS, CoreWeave) | Fees negotiated under competitive pressure; capped revenue share |
| Model D | Infrastructure Independence | A sufficiently large laboratory directly finances datacenters, power and specialized compute | OpenAI’s Stargate joint venture (partial) | Capital intensity, depreciation and debt service replace external fees |
A laboratory may move among these models as its scale and bargaining power evolve, and the trajectory of the two leading independent laboratories suggests a common direction of travel. Both began in Model B, bound tightly to a single hyperscaler that supplied capital and compute in exchange for exclusivity and revenue participation. Both have moved decisively into Model C, acquiring second and third sources of gigawatt-scale capacity and using the resulting leverage to renegotiate the terms of the original relationship. And both have taken tentative steps toward Model D, OpenAI through its participation in the Stargate joint venture and Anthropic through commitments whose scale, at $518 billion over a decade, implies a degree of control over dedicated capacity that approaches ownership in all but legal form.[3] The Cloud Tithe is highest in Model B, lowest in Model A, negotiable in Model C and transformed into capital intensity in Model D, and the industry’s migration from B toward C and D is the laboratories’ collective answer to the question of who should keep the sixteen cents.

Section 6: Escaping, Renegotiating or Internalizing the Cloud Tithe
If the preceding sections have established that the Cloud Tithe exists, that it is collected through several contractual forms, and that the institutions collecting it are themselves paying tithes to the layers beneath them, the natural question for a laboratory, and for an investor valuing one, is what can be done about it. This section examines six strategies in roughly ascending order of capital intensity: direct distribution, multicloud competition, custom silicon, datacenter ownership, direct energy procurement and, finally, the most elegant strategy of all, which is to need less infrastructure in the first place. It closes by asking under what conditions the tithe is likely to decline and under what conditions it is likely to rise, because the answer to that question, rather than the existence of any single strategy, will determine the distribution of margin across the Five-Layer AI Economy over the remainder of the decade.
6.1 Direct Distribution
The simplest way to reduce marketplace fees is to sell directly, and the fact that the leading laboratories have not done so to a greater degree is itself informative about what the fee purchases. Direct enterprise distribution at the scale of a $65 billion run-rate business requires sales teams numbering in the thousands, billing infrastructure capable of handling consumption-based pricing across hundreds of thousands of accounts, customer support, regulatory compliance across dozens of jurisdictions, security certifications such as FedRAMP and SOC 2 that take years to obtain and maintain, procurement relationships with purchasing departments that have already standardized on a small number of approved vendors, identity management that integrates with the customer’s existing directory services, and global availability in regions where data-residency rules constrain where inference may be performed. The cloud marketplace fee therefore purchases something real, and the laboratory must compare the cost of paying the tithe with the cost of recreating the institution that collects it. Anthropic’s disclosure that consumption-based revenue of roughly $3.8 billion dwarfed subscription revenue of $789 million in 2025, and that it expects consumption to remain the substantial majority of revenue for the foreseeable future, suggests that the enterprise channel, where the marketplace fee is levied, is precisely the channel on which the company’s growth depends.[1] A laboratory cannot easily escape a tithe that is levied on its most important customers through the procurement systems those customers have already chosen.
6.2 Multicloud Competition
A second strategy is supplier diversification, which the paper has already examined in the Anthropic and OpenAI cases but which deserves a more general statement here. If several cloud companies can run the same frontier model efficiently, the laboratory gains negotiating leverage with each of them, and the size of that leverage is a direct function of how easily workloads can be moved. Hardware portability therefore acquires economic significance that has nothing to do with engineering elegance. Software optimized exclusively for one accelerator creates technological lock-in that the accelerator’s owner can monetize; a model that can be served efficiently on Nvidia GPUs, Google TPUs and Amazon Trainium possesses infrastructure optionality, and that optionality can be converted into financial leverage at every contract renewal. Anthropic’s stated practice of training and serving across all three families, and OpenAI’s April 2026 success in capping its Microsoft revenue share after acquiring Oracle, AWS and CoreWeave capacity, are the two clearest demonstrations that the strategy works.[26][57] Its cost is the engineering effort required to maintain performance parity across heterogeneous silicon, and its limit is the willingness of each provider to continue competing for a customer who has visibly committed to never depending on any of them.
6.3 Custom Silicon
Eventually the frontier laboratories may participate more directly in chip design, and the Anthropic–Broadcom relationship suggests that the first steps in that direction have already been taken, albeit through a hyperscaler’s architecture rather than the laboratory’s own. Participation in silicon design does not necessarily mean constructing fabrication plants, which remain the province of a handful of foundries and require capital commitments and process expertise that no laboratory possesses. A company can design accelerators while relying on outside foundries, packaging companies, memory suppliers and datacenters, as Google has done with TPUs and Amazon with Trainium. Custom silicon can reduce the accelerator vendor’s margin, which at Nvidia’s 75 percent gross margin is the largest single tithe in the stack, but it creates another series of dependencies, on the foundry, on the advanced-packaging capacity that has become a bottleneck in its own right, and above all on the three memory producers whose HBM capacity is sold out through 2027.[12][49] The Cloud Tithe can therefore migrate downward rather than disappear. A laboratory that designed its own chip would stop paying Nvidia’s margin and start paying TSMC’s, SK hynix’s and Broadcom’s, and whether the sum of those is smaller than the first is an empirical question whose answer depends on scale.
6.4 Owning the Datacenter
Larger laboratories may increasingly finance dedicated datacenters, and the Stargate program, in which OpenAI participates as a joint-venture partner alongside Oracle and SoftBank, is the most advanced example. Again, ownership changes the economic form of the infrastructure claim without eliminating it. Instead of paying cloud margin, the laboratory pays construction costs, debt service, accelerator depreciation on a schedule that has been shortening as hardware generations accelerate, maintenance, land, networking, cooling and electricity. Vertical integration converts a variable external payment into capital intensity, and the economically relevant comparison is therefore not between cloud cost and zero cost but between the external infrastructure margin, which is the price the cloud charges above its own cost, and the internal infrastructure cost, which is what the laboratory would pay to replicate that capacity itself including the cost of the capital required to do so.
External Infrastructure Margin versus Internal Infrastructure Cost
For a hyperscaler with decades of operating experience, a global procurement organization and the lowest cost of capital in the corporate world, the external margin may be smaller than the laboratory’s internal cost, in which case paying the tithe is rational. For a laboratory whose scale has reached the point at which it is contracting for gigawatts, the calculation may invert, and Oracle’s own disclosure that a large share of its new contracts are structured through customer prepayments or bring-your-own-hardware arrangements suggests that the boundary between renting and owning is already becoming blurred.[42] When the customer finances the supplier’s construction through prepayments, the customer is in substance a part-owner of the capacity, and the tithe it pays is in part a return on its own capital.
6.5 Owning or Contracting Power
At sufficient scale, infrastructure strategy eventually reaches Layer 1, and the evidence of 2026 is that it already has. Long-duration power-purchase agreements, nuclear contracts, dedicated generation and behind-the-meter power systems have become part of model economics, and the IEA reported that the pipeline of data-centre offtake agreements with small modular reactors grew from 25 gigawatts at the end of 2024 to 45 gigawatts by the end of 2025.[62] The closer model laboratories move toward direct energy procurement, the clearer the Five-Layer AI Economy becomes, because each layer’s attempt to internalize the layer beneath it reveals that there is always another layer further down. Layer 4 can attempt to internalize Layer 3 by building datacenters. Layer 3 can internalize Layer 2 by designing silicon. Layer 2 nevertheless depends upon fabrication and memory, which depend upon their own capital-intensive supply chains. And all of them ultimately depend upon Layer 1, whose scarcity is governed by permitting timelines, transmission constraints and the physics of generation rather than by anything a technology company can accelerate through capital alone. There is always another layer beneath the apparent bottom, and the deepest layer sets the floor beneath every margin above it.
6.6 Inference Efficiency as Negotiating Power
The most elegant escape from the Cloud Tithe may not be owning infrastructure at all. It may be needing less of it. Model compression, sparsity, improved architectures, caching, speculative decoding, better quantization and specialized inference silicon can all reduce the infrastructure required to produce a unit of useful intelligence, and the Stanford AI Index’s finding that inference prices for a fixed capability have fallen by between nine and nine hundred times per year depending on the task is evidence that the industry has already captured enormous efficiency gains.[9] The proposition that follows is one of the paper’s central claims, and it can be stated compactly: model efficiency is infrastructure bargaining power. A laboratory that can produce equivalent intelligence with half the compute requirement can tolerate higher cloud prices, serve more customers from the same contracted capacity, or negotiate its next contract from a stronger position, because its demand for the tithed resource is lower relative to the revenue that resource generates. Anthropic’s achievement of positive adjusted operating income in the second quarter of 2026, on revenue of more than $11.5 billion, is the first public evidence that a frontier laboratory can clear its compute and distribution claims with margin to spare, and the investor commentary attributing that result in part to token efficiency suggests that the market has already begun to price efficiency as a determinant of the tithe rather than merely as an engineering virtue.[24][27]
The efficiency strategy also has a limit, and it is the same limit identified in Section 1. Falling unit costs induce greater consumption, and the agentic workloads that now account for a growing share of enterprise usage multiply the number of model calls per task by orders of magnitude. Stanford’s Brynjolfsson, who has spent two decades studying the lag between the invention of a general-purpose technology and the productivity gains it eventually delivers, observed in early 2026 that the productivity take-off from AI was finally becoming visible and that a cohort of power users was automating entire workstreams with agents, completing in hours work that had previously taken weeks.[63] Every such workstream is a stream of tokens, and every token is a claim on the infrastructure layer. Efficiency reduces the tithe per unit of intelligence; agentic adoption increases the units. Which effect dominates will determine whether the aggregate tithe rises or falls, and the honest answer in October 2026 is that both are accelerating at once.
6.7 When Does the Tithe Decline?
The paper has resisted, and continues to resist, the assumption that today’s fee structures are permanent, and it closes this section by setting out, as explicitly as the evidence permits, the forces that could push the Cloud Tithe downward and the forces that could push it upward.
| Forces Pushing the Tithe Downward | Forces Pushing the Tithe Upward |
| Competition among clouds and the emergence of specialized providers with excess capacity | Persistent power scarcity and multi-year transmission and permitting constraints |
| Oversupply of accelerator capacity following the current buildout, as occurred in telecommunications after 2000 | High-bandwidth memory shortages with capacity committed through 2027 across a three-firm oligopoly |
| Standardized AI infrastructure and open serving stacks that reduce switching costs | Concentration of advanced accelerators and advanced packaging in a small number of suppliers |
| Improved model portability across GPU, TPU and Trainium families | Enterprise marketplace dependence rising as a share of revenue even at scale |
| Direct enterprise adoption as laboratories build their own sales and compliance machinery | Sovereign and regional cloud requirements that fragment the market and favor incumbent operators |
| Falling inference costs and improving token efficiency | Increasingly compute-intensive reasoning that multiplies tokens per answer |
| Model commoditization that shifts leverage from the model toward the channel and the customer | Agentic systems producing far more inference per user and per task |
The Cloud Tithe should therefore be treated as a dynamic economic variable rather than as a predetermined percentage, and the reader will notice that several forces appear, in different forms, on both sides of the table. Model commoditization reduces the tithe a laboratory can be charged for compute while increasing the tithe it must pay for distribution, because a commoditized model is one the customer does not demand by name. Falling inference costs reduce the tithe per token while inducing the agentic workloads that increase tokens per task. The net direction is not determinable from first principles, and this is precisely why the public disclosure of frontier-laboratory economics matters: it converts a question that could previously only be argued into one that can be measured, filing by filing, for the rest of the decade.

Section 7: What Have We Learned? Eight Pillars
A working paper of this length owes its reader a synthesis, and this section offers one in the form of eight pillars, each of which states a lesson that the evidence of 2025 and 2026 supports and that the Five-Layer framework helps to organize. The first five correspond to the structure of the argument as originally conceived; the final three emerged from the research itself, and in particular from reading the infrastructure layer’s own financial statements alongside the laboratory’s prospectus.
Pillar 1 — Intelligence Is Not Pure Software
The first and most fundamental lesson is that frontier AI should not automatically inherit the economic assumptions of the traditional software industry. Useful intelligence requires continuous computation. Continuous computation requires physical infrastructure. Physical infrastructure creates recurring economic claims that software reproduction never did. The marginal cost of software reproduction approached zero; the marginal cost of intelligence may decline dramatically, and the evidence that it has done so is overwhelming, but it does not disappear, and the aggregate claim grows with consumption even as the unit claim falls. That difference changes valuation, because it means that gross margin must be measured after compute and distribution rather than before; it changes competition, because it means that access to scarce infrastructure is a competitive advantage in a way that access to servers never was; and it changes industrial organization across the entire Five-Layer AI Economy, because it gives the lower layers a durable claim on the upper layers that the software era had dissolved.
Pillar 2 — Distribution Is Becoming Infrastructure
The second lesson is that the cloud marketplace should no longer be understood merely as a sales channel. It is becoming part of the infrastructure through which enterprise intelligence is delivered, and the Anthropic data, in which the marketplace share of revenue rose from 11 percent to 47 percent in two years and the marketplace share of receivables collection rose to 60 percent, describe a channel that has become load-bearing. A company with pre-existing relationships with millions of businesses possesses something frontier laboratories cannot build overnight, which is institutional distribution: the accumulated procurement approvals, security certifications, billing integrations and budgetary commitments that allow an enterprise to begin consuming a new service without a new contract. The same enterprise may prefer purchasing Claude through AWS, Azure or Google Cloud because those platforms already satisfy its requirements, and the marketplace therefore becomes an economic moat for the hyperscaler even in a world where compute itself has become abundant. Compute capacity can eventually become abundant, as every previous infrastructure buildout has eventually produced oversupply. Enterprise trust and distribution may remain scarce for considerably longer, and the tithe levied on distribution may therefore outlast the tithe levied on compute.
Pillar 3 — The AI Economy Is Built on Overlapping Roles
The third lesson is that conventional categories such as supplier, customer, investor and competitor have become inadequate for describing the relationships at the frontier of the industry. Amazon can invest in Anthropic, supply Anthropic with computing infrastructure, distribute Claude, receive fees associated with Claude sales, record $53 billion of quarterly gains on its Anthropic stake, host OpenAI’s models on the same platform, and simultaneously build competing AI products and silicon. Google occupies similarly overlapping positions with respect to the same laboratory. Microsoft and OpenAI demonstrate another configuration of the same phenomenon, in which the cloud provider holds a 27 percent equity stake, a non-exclusive license to the laboratory’s intellectual property through 2032 and a capped revenue share through 2030, while previewing its own competing models. This interdependence is likely to define the next phase of the Five-Layer AI Economy, and its central paradox can be stated simply: competition will increasingly occur inside partnerships, while partnerships will increasingly occur between competitors. Analysts who model a laboratory’s competitive position by examining its rivals and its suppliers as separate lists will systematically misunderstand it.
Pillar 4 — Public Markets Will Force Infrastructure Economics Into the Open
The fourth lesson is that AI initial public offerings may fundamentally improve our understanding of frontier-model economics, because private companies can operate for years without disclosing detailed infrastructure costs, marketplace concentration, revenue-sharing arrangements or long-duration compute obligations, while public companies cannot keep those economics invisible indefinitely. Anthropic’s confidential prospectus has already exposed relationships that previously could only be estimated, and it has done so before the company has sold a single share. Future filings from AI laboratories, infrastructure companies and datacenter operators may reveal much more, and the accounting controversy between Anthropic’s gross presentation and OpenAI’s net presentation guarantees that the first question analysts will ask of every subsequent filing is how much of the reported revenue the laboratory actually keeps. Investors will eventually need metrics that distinguish gross AI revenue from the amount economically retained after cloud distribution and compute expense, and the hierarchy proposed in Section 1, from Direct Revenue through Marketplace Revenue and Infrastructure-Adjusted Revenue to Compute Contribution Margin and Full Intelligence Margin, is offered as a starting point. The market may discover, as it works through those metrics, that AI revenue and AI margin are two very different things, and that the gap between them is the Cloud Tithe. The disclosure regime that will produce those metrics is itself an institution, and Stanford’s Brynjolfsson has warned that the institutions needed to govern transformative AI are being built more slowly than the technology they are meant to govern.
Institutions take years to construct, and transformative AI may not wait for them.
— Erik Brynjolfsson, Stanford Graduate School of Business [64]
The accounting and disclosure vocabulary for frontier-model economics is one such institution, and the Anthropic prospectus is the first draft of it.
Pillar 5 — Vertical Integration Is Fundamentally About Bargaining Power
The fifth lesson is that AI companies may increasingly build infrastructure not because owning datacenters, chips or power plants is inherently attractive, but because ownership, or the credible threat of it, creates negotiating leverage. The possibility of self-supply changes the price charged by external suppliers even when self-supply never occurs. Multicloud capability changes negotiations with any single cloud, as OpenAI’s capped revenue share demonstrates. Custom silicon changes negotiations with accelerator vendors, as the hyperscalers’ Trainium and TPU programs demonstrate with respect to Nvidia. Direct distribution changes negotiations with marketplaces. Dedicated generation changes negotiations over electricity. Vertical integration therefore functions as an economic threat point rather than as an end in itself, and a frontier laboratory does not necessarily need to own the entire Five-Layer AI Economy in order to protect its margin. It needs enough credible alternatives at each layer to prevent any one layer from capturing an excessive proportion of the value generated above it, and the cost of maintaining those alternatives, in engineering effort, in duplicated commitments and in capital, is the premium the laboratory pays to keep the tithe negotiable.
Pillar 6 — The Tithe Is a Dynamic Variable Governed by Relative Scarcity
The sixth lesson, which emerged from the attempt to determine whether the sixteen-cent figure would rise or fall, is that the Cloud Tithe is governed by the relative scarcity of what each layer contributes rather than by any fixed contractual convention. When accelerators and power are the binding constraints, as they were in 2025 and 2026, the infrastructure layer collects a rising share, and the hyperscalers’ own statements that demand exceeds capacity, together with their 35 to 40 percent cloud operating margins, confirm that the share was rising. When the model is the thing enterprises demand by name, and when several providers can supply equivalent capacity, the laboratory collects a rising share, and OpenAI’s capped revenue share and Anthropic’s first positive operating quarter are early evidence that this phase may be beginning for the leading laboratories. The history of every previous infrastructure buildout, from railways through telecommunications to public cloud itself, suggests that scarcity eventually gives way to oversupply, and that the layer which collected the tithe during the buildout becomes the layer that competes on price afterward. The MIT economist and Nobel laureate Daron Acemoglu, who has been the most persistent academic skeptic of the productivity case for the current buildout, framed the risk to the infrastructure layer in exactly these terms in September 2026.
…at some point people are going to sour on AI, and that will bring down investments.
— Daron Acemoglu, Institute Professor, MIT [65]
Acemoglu’s own estimate, published in June 2026, is that AI will deliver roughly 0.55 percent of cumulative total-factor-productivity gain over the coming decade, a fraction of the figures implied by current infrastructure spending.[66] One need not accept that estimate to recognize its implication for the tithe: if the productivity gains that justify the buildout do not arrive on schedule, the infrastructure layer’s scarcity will dissolve into oversupply, and the tithe it collects will fall not because the laboratories renegotiated it but because the collectors overbuilt. The sixteen cents is a reading on an instrument, not a law.
Pillar 7 — Energy Is the Final Collector
The seventh lesson is that the cascade of claims through the Five-Layer AI Economy terminates in Layer 1, and that the energy layer is the only one whose scarcity cannot be relieved by capital alone on the timescales that matter. The IEA’s projection that data-centre electricity consumption will roughly double by 2030 while AI-focused consumption triples, its observation that AI server power density increased elevenfold between 2020 and 2025, and its warning that the industry is approaching the limits of today’s power-delivery and cooling technologies together describe a constraint governed by physics, permitting and transmission rather than by the willingness of technology companies to spend.[50][51] The White House’s decision to organize an entire pillar of national AI policy around datacenter permitting and grid development is political confirmation of the same point.[52] Every layer above energy can, in principle, be duplicated by a sufficiently well-capitalized entrant; a laboratory can rent a second cloud, a cloud can design a second chip, a chip designer can qualify a second foundry. Only the grid cannot be duplicated on demand, and the institutions that control dedicated generation, long-duration power contracts and grid interconnection rights are therefore positioned to collect the last and least negotiable tithe of all. The hyperscalers understand this, which is why their capital expenditure increasingly includes generation and why the IMF’s managing director, assessing the global outlook in late September 2026, described the world economy as caught between an energy shock and an AI investment boom that are pulling in opposite directions.
The positive demand shock from AI is pushing it up.
— Kristalina Georgieva, Managing Director, International Monetary Fund [67]
Georgieva’s broader warning, that the AI boom is only as durable as investor enthusiasm and that the risks are front-loaded because investment accumulates before adoption justifies it, is the macroeconomic expression of Pillar 6, and the fact that she paired it with an energy shock is the macroeconomic expression of Pillar 7.[67]
Pillar 8 — Circularity Is Both the Engine and the Fragility of the System
The eighth and final lesson is that the circular flows of capital, compute and revenue that this paper has described are simultaneously the mechanism by which the frontier of artificial intelligence is being financed and the mechanism by which risk is being concentrated. The same circularity that allows Amazon to record $53 billion of quarterly gains on a laboratory to which it supplies infrastructure, and that allows that laboratory to commit $100 billion to the supplier that invests in it, also means that a disappointment at any node propagates to every other node through balance sheets, backlogs and valuations. The IMF’s 2026 annual report stated the concern directly.
…the payoff from expensive investments in AI, increasingly debt financed, could prove illusory.
— International Monetary Fund, Annual Report 2026 [20]
The Fund’s chief economist had warned in January 2026 of the risk of a market correction if expectations about AI productivity and profitability were not realized, and by July the Fund had lowered its global growth forecast while citing uncertainties surrounding artificial intelligence among the downside risks.[68][69] The relevance of these warnings to the Cloud Tithe is precise. A tithe is sustainable only if the producer on whom it is levied continues to produce, and a tithe collector that has borrowed against future collections, as the hyperscalers and neoclouds increasingly have, is exposed to the producer’s fortunes in a way that a traditional landlord is not. Sequoia Capital’s David Cahn posed the governing question in 2024, when he asked where the revenue to justify the buildout would come from, and his own subsequent estimate that the gap had widened from $600 billion to roughly $840 billion by the end of 2025 suggests that the question remained open even as laboratory revenue grew tenfold.[70]
Where is all the revenue?
— David Cahn, Sequoia Capital [70]
The Anthropic prospectus offers a partial answer, in the form of $4.6 billion of 2025 revenue, $11.5 billion in a single quarter of 2026 and a $65 billion run rate, and it also offers the first precise accounting of how much of that revenue the infrastructure layer retains. The circularity that worries the IMF is, from the laboratory’s perspective, the same circularity that funds its growth, and from the hyperscaler’s perspective, the same circularity that produces its backlog. Whether it proves to be the engine or the fragility of the system will depend on whether intelligence generates enough end-user value, quickly enough, to service every claim in the cascade, and that is a question that no filing can yet answer.

Conclusion: Who Gets Paid Every Time Intelligence Is Used?
The most revealing number inside Anthropic’s confidential IPO filing may not ultimately be its valuation, its annual revenue, its operating loss or even its enormous infrastructure commitments. It may be sixteen cents. Not because sixteen cents represents an immutable law of AI economics, because it does not; Reuters’ calculation applies specifically to Anthropic’s 2025 cloud-marketplace sales through Amazon and Google, not to all Anthropic revenue, not to revenue flowing through Microsoft Azure, and certainly not to every frontier-model company.[1] Its importance is conceptual. The number makes something previously abstract measurable, and in doing so it converts a debate about the industrial structure of artificial intelligence from a matter of assertion into a matter of evidence.
It shows that economic value created by a frontier model does not necessarily remain with the model developer. Part of that value can move downward. The enterprise customer pays for intelligence. The model laboratory recognizes revenue. The cloud marketplace takes a portion for distribution and collection. The cloud provider charges for the accelerator-hours that generated the response. The cloud provider purchases those accelerators from a chip vendor operating at a 75 percent gross margin. The accelerator depends upon memory whose producers have sold their capacity through 2027, upon packaging and fabrication concentrated in a handful of facilities, and upon networking. The datacenter consumes electricity whose supply is governed by permitting and transmission timelines measured in years. And the original customer dollar begins traveling backward through the Five-Layer AI Economy, leaving a fragment at every layer, until what remains in Layer 4 is the Full Intelligence Margin that this paper has argued is the correct measure of a laboratory’s economic achievement.
That is why Cloud Tithe fits this paper. The title is not intended to imply that AWS, Google Cloud, Microsoft or the other infrastructure providers are imposing an unjust tax. They provide enormous economic value: capital that funds the laboratories, compute that trains the models, distribution that reaches the enterprises, reliability and security that the enterprises require, custom silicon that lowers the cost of every token, and access to established markets that no laboratory could build in the time available. The important insight is that in exchange for all of this they may acquire a recurring proportional claim on the economic output of artificial intelligence, and that this is what distinguishes a tithe from an ordinary capital expenditure. A datacenter can be purchased once. A server depreciates. A chip can be replaced. But if a percentage of revenue continues flowing toward infrastructure whenever intelligence is sold, the infrastructure layer has achieved something strategically more valuable than a hardware transaction. It has obtained participation in the growth of intelligence itself.
This reverses the conventional narrative of the AI stack. We often assume that value moves upward, from energy through chips and datacenters to models and finally to applications, so that each layer is merely an input to the one above it. Cloud Tithe reveals the counterflow, in which applications generate revenue that flows to models, which flows to the cloud, which flows to the chips and the memory and the grid. The technological value chain moves upward. The economic claim can move downward. And the two flows are mediated by a small number of institutions that sit at both ends of the pipe, supplying the compute that makes intelligence possible and collecting a share of the revenue that intelligence produces. This is why the concept belongs beside the earlier Central Bank of AI framework. Central Bank of AI asked who controls the supply of the scarce computational liquidity required to expand artificial intelligence. Cloud Tithe asks what happens after that computational liquidity has been transformed into commercial intelligence. Who receives a share every time the intelligence is sold? Who collects revenue without having invented the underlying model? Who owns the infrastructure that a frontier laboratory cannot easily abandon? Who controls the enterprise channels through which artificial intelligence reaches corporations? And at what point does a model company become large enough to renegotiate those relationships?
Those questions will become increasingly important as frontier laboratories move toward public markets, and the evidence of 2026 suggests that the answers are already shifting. OpenAI has capped its revenue share with Microsoft by acquiring alternative capacity. Anthropic has diversified across three accelerator families and three marketplaces, committed to half a trillion dollars of infrastructure that approaches ownership in substance, and recorded its first quarter of positive adjusted operating income. The hyperscalers, for their part, have begun raising equity and issuing debt on a scale that makes them dependent on the laboratories’ continued growth, and they have begun selling their own silicon externally in order to extend their tithe-collecting reach further down the stack. The emerging competition may therefore not simply be OpenAI versus Anthropic, Claude versus GPT, Gemini versus other models, or Nvidia versus custom accelerators. A deeper competition is forming between the layers of the AI economy over who captures the margin created by intelligence. Layer 4 wants to preserve the economics of the model. Layer 3 wants compensation for infrastructure and distribution. Layer 2 wants compensation for scarce silicon and scarcer memory. Layer 1 wants compensation for increasingly scarce and strategically located electricity. And Layer 5 wants to convert all of those inputs into applications whose value to customers exceeds the combined claims beneath them, because if it cannot, no layer will be paid for long.
The companies that dominate the AI economy of 2027 to 2030 may therefore not simply be those that create the most capable intelligence. They may be the companies that become indispensable enough to collect a small portion of the value whenever somebody else creates, distributes or consumes it. That is the deeper meaning of Cloud Tithe. Artificial intelligence may create extraordinary new economic value, and the revenue trajectories disclosed in 2026 suggest that it is already beginning to. But before that value reaches the bottom line of the company that created the model, increasingly powerful institutions beneath it, in the cloud, in the fab, in the memory foundry and at the substation, may already be waiting for their share. The sixteen cents is the first time one of them has been counted in public. It will not be the last.

Endnotes:
[1] Echo Wang and Krystal Hu, Reuters, “Exclusive-Anthropic IPO prospectus lays bare deep dependence on Big Tech partners,” September 29, 2026. https://www.933thedrive.com/2026/09/29/exclusive-anthropic-ipo-prospectus-lays-bare-deep-dependence-on-big-tech-partners/
[2] The Next Web, “Anthropic lost $42bn in 2025 as revenue grew 12-fold, Reuters reports,” September 2026. https://thenextweb.com/news/anthropic-ipo-prospectus-42bn-loss-518bn-compute
[3] CNBC (citing Reuters), “Anthropic’s IPO prospectus shows sweeping AI vision, surging costs,” September 28, 2026. https://www.cnbc.com/2026/09/28/anthropics-ipo-prospectus-shows-sweeping-ai-vision-surging-costs-reuters.html
[4] Reuters / CTech, “Anthropic relies on Amazon and Google for nearly half its sales,” September 30, 2026. https://www.calcalistech.com/ctechnews/article/r8sh14ux4
[5] Capital Brief, “Anthropic’s IPO prospectus reveals USD4.6b revenue surge — and USD8.1b operating loss,” September 2026. https://www.capitalbrief.com/briefing/anthropics-ipo-prospectus-reveals-usd46b-revenue-surge-and-usd81b-operating-loss-502742cd-1025-43ee-ab7b-cf4c551fbce5/
[6] TechCrunch, “Anthropic takes $5B from Amazon and pledges $100B in cloud spending in return,” April 20, 2026. https://techcrunch.com/2026/04/20/anthropic-takes-5b-from-amazon-and-pledges-100b-in-cloud-spending-in-return/
[7] Anthropic, “Anthropic expands partnership with Google and Broadcom for multiple gigawatts of next-generation compute,” April 7, 2026 (statement of Krishna Rao, CFO). https://www.anthropic.com/news/google-broadcom-partnership-compute
[8] Stanford Institute for Human-Centered Artificial Intelligence, “AI Index 2025: State of AI in 10 Charts,” April 2025. https://hai.stanford.edu/news/ai-index-2025-state-of-ai-in-10-charts
[9] R&D World, “AI’s great compression: 20 charts show vanishing gaps but still-soaring costs” (summarizing the Stanford AI Index), 2025. https://www.rdworldonline.com/ais-great-compression-20-charts-show-vanishing-gaps-but-still-soaring-costs/
[10] CNBC, “Anthropic tells investors annualized revenue run rate climbed to $65 billion in July,” August 17, 2026. https://www.cnbc.com/2026/08/17/anthropic-says-annualized-revenue-climbed-to-65-billion-in-july.html
[11] McKinsey & Company, “Is the AI productivity story at a turning point?” (podcast with Erik Brynjolfsson, Stanford Digital Economy Lab), July 31, 2026. https://www.mckinsey.com/capabilities/people-and-organization/our-insights/is-the-ai-productivity-story-at-a-turning-point
[12] NVIDIA Corporation, “NVIDIA Announces Financial Results for Second Quarter Fiscal 2027,” Form 8-K, August 26, 2026 (statement of Jensen Huang). https://www.sec.gov/Archives/edgar/data/0001045810/000104581026000073/q2fy27pr.htm
[13] Finimize, “Anthropic’s IPO Filing Shows How Tied It Is To Big Tech,” September 2026. https://finimize.com/content/anthropics-ipo-filing-shows-how-tied-it-is-to-big-tech
[14] Loraine Lawson, The New Stack, “Amazon and Anthropic deepen AI ties with a $100B AWS commitment,” April 21, 2026. https://thenewstack.io/anthropic-amazon-aws-investment/
[15] Broadcom Inc., Form 8-K, April 6, 2026, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/1730168/000119312526144028/d87999d8k.htm
[16] Reuters via MarketScreener, “Anthropic plans an IPO as early as 2026, FT reports,” December 2, 2025 (noting the Microsoft/Nvidia investment and $30 billion Azure commitment). https://www.marketscreener.com/news/anthropic-plans-an-ipo-as-early-as-2026-ft-reports-ce7d51d9d08cf326
[17] Yahoo Finance, “Anthropic’s IPO is a $300 billion test for Amazon,” September 2026 (reproducing Andy Jassy’s April 20, 2026 statement). https://finance.yahoo.com/technology/ai/articles/anthropics-ipo-300-billion-test-014700775.html
[18] Amazon.com, Inc., “Amazon.com Announces Second Quarter Results,” Form 8-K Exhibit 99.1, July 30, 2026. https://www.sec.gov/Archives/edgar/data/0001018724/000101872426000024/amzn-20260630xex991.htm
[19] Alphabet Inc., “Alphabet Announces First Quarter 2026 Results,” Form 8-K Exhibit 99.1, April 29, 2026. https://www.sec.gov/Archives/edgar/data/0001652044/000165204426000043/googexhibit991q12026.htm
[20] International Monetary Fund, Annual Report 2026, “AI: Deployment and Disruption.” https://www.imf.org/annual-report/2026/in-focus/ai-deployment-and-disruption/
[21] Jon Markman, Forbes, “Amazon $33 Billion Anthropic Deal And The Limits Of AI Infrastructure,” April 22, 2026. https://www.forbes.com/sites/jonmarkman/2026/04/22/amazon-33-billion-anthropic-deal-and-the-limits-of-ai-infrastructure/
[22] CNBC, “Amazon’s AWS posts fastest growth since 2021, citing AI and chip demand,” July 30, 2026. https://www.cnbc.com/2026/07/30/aws-earnings-q2-2026.html
[23] The Register, “Microsoft and OpenAI’s open relationship is now official,” April 27, 2026. https://www.theregister.com/2026/04/27/microsofts_and_openai_change_relationship/
[24] CNBC, “Anthropic revenue reportedly jumps to more than $11.5 billion in second quarter,” August 15, 2026. https://www.cnbc.com/2026/08/15/anthropic-revenue-jumps-to-over-11point5-billion-in-q2-report.html
[25] Quartz via Yahoo Finance, “Anthropic revenue run rate hits $65 billion ahead of IPO,” August 18, 2026. https://finance.yahoo.com/technology/ai/articles/anthropic-revenue-run-rate-hits-111710007.html
[26] HPCwire, “Anthropic Signs Google, Broadcom Deal to Add Multi-Gigawatt TPU Capacity,” April 7, 2026. https://www.hpcwire.com/off-the-wire/anthropic-signs-google-broadcom-deal-to-add-multi-gigawatt-tpu-capacity/
[27] Axios, “Anthropic’s revenue run rate reportedly surpasses $65 billion pre-IPO,” August 17, 2026 (quoting Gavin Baker, Atreides Management). https://www.axios.com/2026/08/17/anthropic-revenue-run-rate-ipo-openai
[28] Investing.com, “Earnings call transcript: Amazon tops Q2 2026 estimates as AWS growth accelerates,” July 30, 2026. https://www.investing.com/news/transcripts/earnings-call-transcript-amazon-tops-q2-2026-estimates-as-aws-growth-accelerates-93CH-4826442
[29] Alphabet Inc., “2026 Q2 Earnings Call,” Alphabet Investor Relations, July 22, 2026 (remarks of Anat Ashkenazi, CFO). https://abc.xyz/investor/events/event-details/2026/2026-Q2-Earnings-Call-2026-GgTAq7Is0z/default.aspx
[30] Investing.com, “Alphabet Q2 2026 slides: 24% revenue growth, cloud surges despite capex,” July 22, 2026. https://www.investing.com/news/company-news/alphabet-q2-2026-slides-24-revenue-growth-cloud-surges-despite-capex-93CH-4807148
[31] Microsoft Corporation, “Microsoft Cloud and AI Strength Fuels Fourth Quarter Results,” Form 8-K Exhibit 99.1, July 29, 2026. https://www.sec.gov/Archives/edgar/data/0000789019/000119312526323632/msft-ex99_1.htm
[32] Microsoft, “Fiscal Year 2026 Fourth Quarter Earnings Conference Call,” July 29, 2026. https://www.microsoft.com/en-us/investor/events/fy-2026/earnings-fy-2026-q4
[33] CNBC, “Microsoft jumps 8% as it boosts capital spending plans, citing demand,” July 29, 2026. https://www.cnbc.com/2026/07/29/microsoft-msft-q4-earnings-report-2026.html
[34] TradingView News (Leverage Shares), “Amazon Q2 2026 Earnings Shows AWS Growth Accelerates,” August 2026. https://www.tradingview.com/news/leverage_shares:2508da40f094b:0-amazon-q2-2026-earnings-shows-aws-growth-accelerates/
[35] Alphabet Inc., Form 10-Q for the quarter ended June 30, 2026, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001652044/000165204426000071/goog-20260630.htm
[36] Alphabet Inc., Form 8-K, June 1, 2026 (concurrent public offerings and at-the-market program to fund AI infrastructure). https://www.sec.gov/Archives/edgar/data/0001652044/000119312526257724/d83560dex991.htm
[37] Microsoft Corporation, Form 10-K for the fiscal year ended June 30, 2026, U.S. Securities and Exchange Commission (OpenAI revenue and partnership disclosures). https://www.sec.gov/Archives/edgar/data/0000789019/000119312526323660/msft-20260630.htm
[38] NVIDIA Corporation, Form 10-Q for the quarter ended July 26, 2026, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001045810/000104581026000075/nvda-20260726.htm
[39] NVIDIA Corporation, Form 10-Q for the quarter ended April 26, 2026, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001045810/000104581026000052/nvda-20260426.htm
[40] Oracle Corporation, “Oracle Announces Q1 Results Driven by Triple Digit Growth in Cloud Infrastructure Revenues,” September 10, 2026. https://www.oracle.com/news/announcement/q1fy27-earnings-release-2026-09-10/
[41] Oracle Corporation, Form 10-Q for the quarter ended August 31, 2026, U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/0001341439/000119312526389274/orcl-20260831.htm
[42] ERP Today, “Oracle Q1 FY27 Results: $664B Backlog, Negative Cash Flow,” September 11, 2026. https://erp.today/oracle-q1-fy27-results-664b-backlog-ai-contracts/
[43] Data Center Dynamics, “OpenAI signs $300bn cloud deal with Oracle – report,” September 11, 2025. https://www.datacenterdynamics.com/en/news/openai-signs-300bn-cloud-deal-with-oracle-report/
[44] CNBC, “CoreWeave stock pops 14% as revenue doubles on accelerating AI infrastructure demand,” August 11, 2026. https://www.cnbc.com/2026/08/11/coreweave-crwv-q2-earnings-report-2026.html
[45] CoreWeave, Inc., Q2 FY2026 earnings call transcript, Yahoo Finance, August 11, 2026. https://finance.yahoo.com/quote/CRWV/earnings/CRWV-Q2-2026-earnings_call-662772.html
[46] Khan Capital, “CoreWeave Q2 2026 Earnings: The $104 Billion Backlog and the $640 Million Interest Bill,” September 2026. https://khancapitals.com/coreweave-q2-2026-earnings/
[47] Network World, “Samsung warns of memory shortages driving industry-wide price surge in 2026” (interview of Wonjin Lee, Samsung, with Bloomberg), January 2026. https://www.networkworld.com/article/4113772/samsung-warns-of-memory-shortages-driving-industry-wide-price-surge-in-2026.html
[48] Investing.com, “The End of Cheap Memory: Why 2026 Marks a Structural Shift in Tech Economics,” February 2026. https://www.investing.com/analysis/the-end-of-cheap-memory-why-2026-marks-a-structural-shift-in-tech-economics-200675634
[49] MarketWise, “Memory Capacity Is Sold Out Through 2027. Why Have Micron, SK Hynix, and Samsung Shares Tumbled?” August 2026. https://marketwise.com/investing/why-micron-sk-hynix-samsung-stock-is-tumbling-during-memory-shortage/
[50] International Energy Agency, Key Questions on Energy and AI, Executive Summary, April 2026. https://www.iea.org/reports/key-questions-on-energy-and-ai/executive-summary
[51] Enlit World, “AI and data centre electricity use continue to surge, IEA finds,” April 17, 2026. https://www.enlit.world/library/ai-and-data-centre-electricity-use-continue-to-surge-iea-finds
[52] White & Case, “White House unveils comprehensive AI strategy: ‘Winning the race: America’s AI action plan’,” July 2025 (summarizing the White House AI Action Plan of July 23, 2025 and the Executive Order on Accelerating Federal Permitting of Data Center Infrastructure). https://www.whitecase.com/insight-alert/white-house-unveils-comprehensive-ai-strategy-winning-race-americas-ai-action-plan
[53] Reuters via Tiger Brokers, “AI hyperscalers will drive higher US corporate bond supply in 2026, analysts say” (citing Barclays and Bank of America), 2026. https://www.itiger.com/news/2603931398
[54] Rahil Solanki, “The AI Circular Economy: Systemic Risk, Vendor Financing, and the Keystone Problem,” SSRN Working Paper, April 28, 2026. https://papers.ssrn.com/sol3/papers.cfm?abstract_id=6672478
[55] Quartz, “Anthropic gets closer to Google and Broadcom — and says its revenue has tripled in 3 months,” April 7, 2026 (citing Mizuho estimates via CNBC). https://qz.com/anthropic-google-broadcom-tpu-compute-deal-revenue-040726
[56] TechCrunch, “OpenAI expects to cut share of revenue it pays Microsoft by 2030” (citing The Information), 2025. https://techcrunch.com/?p=3004008
[57] Microsoft, “The next phase of the Microsoft-OpenAI partnership,” The Official Microsoft Blog, April 27, 2026. https://blogs.microsoft.com/blog/2026/04/27/the-next-phase-of-the-microsoft-openai-partnership/
[58] CNBC, “OpenAI shakes up partnership with Microsoft, capping revenue share payments,” April 27, 2026. https://www.cnbc.com/2026/04/27/openai-microsoft-partnership-revenue-cap.html
[59] NewMarketPitch, “Can OpenAI actually afford all this compute?” July 2026. https://newmarketpitch.com/blogs/news/frontier-ai-labs-openai-compute-costs
[60] Tech Insider, “OpenAI Raises $122B at $852B Valuation [April 2026]” (Amazon investment and expanded AWS commitment). https://tech-insider.org/openai-110-billion-funding-round-2026/
[61] NVIDIA, “NVIDIA Announces Financial Results for Second Quarter Fiscal 2027,” investor press release, August 26, 2026. https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Announces-Financial-Results-for-Second-Quarter-Fiscal-2027/default.aspx
[62] Sardina Systems, “AI’s Electricity Problem or What the Latest Data Actually Shows” (summarizing IEA, Key Questions on Energy and AI, April 2026). https://www.sardinasystems.com/news/ais-electricity-problem-or-what-the-latest-data-actually-shows/
[63] Fortune via Yahoo Finance, “One of Stanford’s original AI gurus says productivity liftoff has begun…” (on Erik Brynjolfsson’s Financial Times op-ed), February 2026. https://finance.yahoo.com/news/one-stanford-original-ai-gurus-205316027.html
[64] Stanford Graduate School of Business, Insights, “Almost Every Job Has Tasks That AI Can Change” (interview with Erik Brynjolfsson), September 17, 2026. https://www.gsb.stanford.edu/insights/almost-every-job-has-tasks-ai-can-change
[65] MIT Technology Review, “What must happen for AI’s trillion-dollar gamble to pay off,” September 15, 2026 (quoting Daron Acemoglu, MIT). https://www.technologyreview.com/2026/09/15/1144028/ai-infrastructure-boom-investment-bubble-risk/
[66] Fortune, “Nobel Laureate Daron Acemoglu on the ‘brainless’ AI discourse, the myth of capitalism and the Gen Z revolution risk,” June 21, 2026. https://fortune.com/2026/06/21/nobel-laureate-daron-acemoglu-ai-productivity-capitalism-democracy/
[67] Semafor, “IMF chief warns AI boom is masking economic fragility from oil shocks” (interview with Kristalina Georgieva), September 28, 2026. https://www.semafor.com/article/09/28/2026/imf-chief-warns-ai-boom-is-masking-economic-fragility-from-oil-shocks
[68] Taipei Times (AFP), “IMF lifts 2026 global growth forecast but flags AI, trade risks,” January 20, 2026 (quoting Pierre-Olivier Gourinchas, IMF Chief Economist). https://www.taipeitimes.com/News/biz/archives/2026/01/20/2003850876
[69] Business Standard (PTI), “Global economy in tug-of-war between oil shock and AI boom: IMF chief,” August 26, 2026. https://www.business-standard.com/world-news/global-economy-in-tug-of-war-between-oil-shock-and-ai-boom-imf-chief-126082600327_1.html
[70] David Cahn, Sequoia Capital, “AI’s $600B Question,” June 2024. https://www.sequoiacap.com/article/ais-600b-question/